3defense
4albion
Samuel Johnson 360x1000
Thomas Piketty1 360x1000
Adam Gopnik 360x1000
George F Wil...360x1000
2jesusandjohnwayne
Brendan Beehan 360x1000
Maria Popova 360x1000
1theleasofus
Lafayette and Jefferson 360x1000
Gilgamesh 360x1000
Mark V Holmes 360x1000
Margaret Fuller5 360x1000
2gucci
Margaret Fuller 2 360x1000
James Gould Cozzens 360x1000
Margaret Fuller4 360x1000
3confidencegames
1madoff
Richard Posner 360x1000
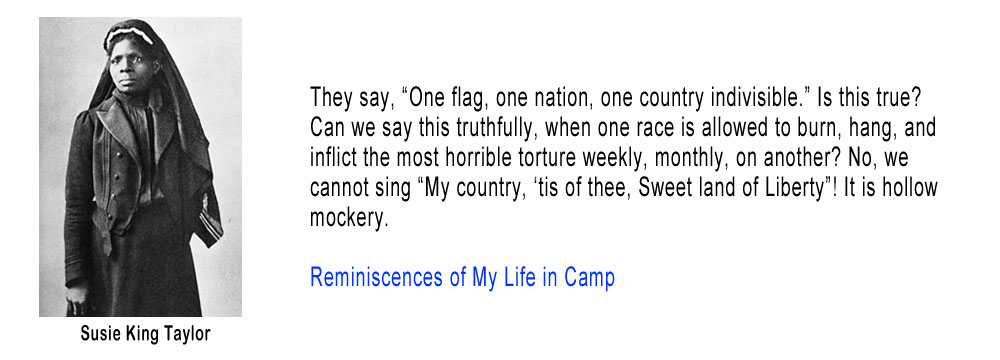
Susie King Taylor 360x1000
1albion
3theleastofus
7albion
Edmund Burke 360x1000
AlexRosenberg
499
lifeinmiddlemarch1
2trap
2confidencegames
5confidencegames
1transcendentalist
2falsewitness
1lookingforthegoodwar
299
Margaret Fuller 360x1000
10abion
lifeinmiddlemarch2
Anthony McCann1 360x1000
Ruth Bader Ginsburg 360x1000
1empireofpain
3paradise
2theleastofus
2albion
5albion
Margaret Fuller3 360x1000
Susie King Taylor2 360x1000
Thomas Piketty2 360x1000
Spottswood William Robinson 360x1000
1paradide
3albion
Margaret Fuller1 360x1000
11632
Thomas Piketty3 360x1000
Stormy Daniels 360x1000
2transadentilist
199
2lookingforthegoodwar
1falsewitness
storyparadox2
1lafayette
storyparadox3
LillianFaderman
Storyparadox1
11albion
6albion
1jesusandjohnwayne
Learned Hand 360x1000
George M Cohan and Lerarned Hand 360x1000
Mary Ann Evans 360x1000
1lauber
14albion
Betty Friedan 360x1000
1defense
Maurice B Foley 360x1000
2lafayette
Tad Friend 360x1000
4confidencegames
Office of Chief Counsel 360x1000
Anthony McCann2 360x1000
399
1trap
2paradise
6confidencegames
8albion'
1gucci
9albion
2defense
1confidencegames
12albion
7confidencegames
Margaret Fuller2 360x1000
13albion

Lu Gauthier of the Boston Tax Institute  has given me permission to reproduce his email blasts.  BTI is a great value for live tax continuing professional education.  If you decided to contact BTI because you read about it here, be sure to mention it to Lu. It won’t get you a discount or me a commission, but it will show him that this blogging thing is a thing.


WILLIAM D. & CHRISTINE J. EVANS v. COMMISSIONER OF REVENUE Docket Nos. C298827 & C310439
         
In a very important Domicile case, the ATB held that Mr. and Mrs. Evans were not domiciled in Massachusetts. The ATB relied heavily on their testimony and other evidence that their decision to move to Florida was because of their desire to live in a setting optimal for Mrs. Evans’ medical condition.
This ruling was made based on all of the evidence. The Board found and ruled that the appellants were physically present in Massachusetts for 150 days in 2001; 166 days in 2002; 165 days in 2003; and 169 days in 2005 and were nonresidents.  While generally I do not recommend that a client spend that many days in Massachusetts, the burden of proving domicile will rest with the individual and clearly the Evans carried the day.  
Domicile is something I focus on a lot, so there is a good chance I will write something on this case for forbes.com.