11632
Susie King Taylor2 360x1000
George M Cohan and Lerarned Hand 360x1000
3albion
2transadentilist
storyparadox3
1lafayette
Thomas Piketty1 360x1000
1defense
14albion
1lookingforthegoodwar
storyparadox2
12albion
Anthony McCann2 360x1000
Anthony McCann1 360x1000
2albion
2jesusandjohnwayne
2theleastofus
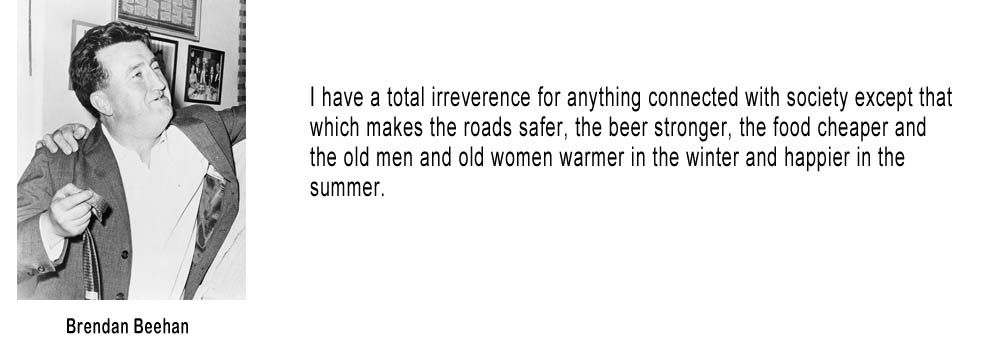
Brendan Beehan 360x1000
1theleasofus
199
Margaret Fuller5 360x1000
Margaret Fuller3 360x1000
2trap
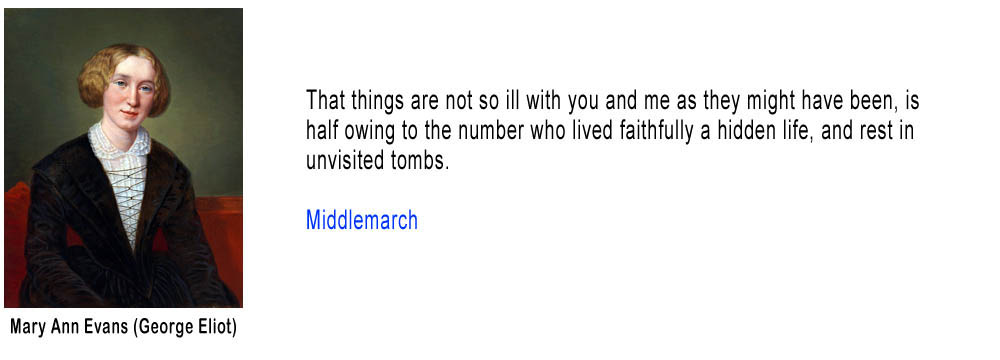
Mary Ann Evans 360x1000
5albion
Thomas Piketty3 360x1000
3confidencegames
299
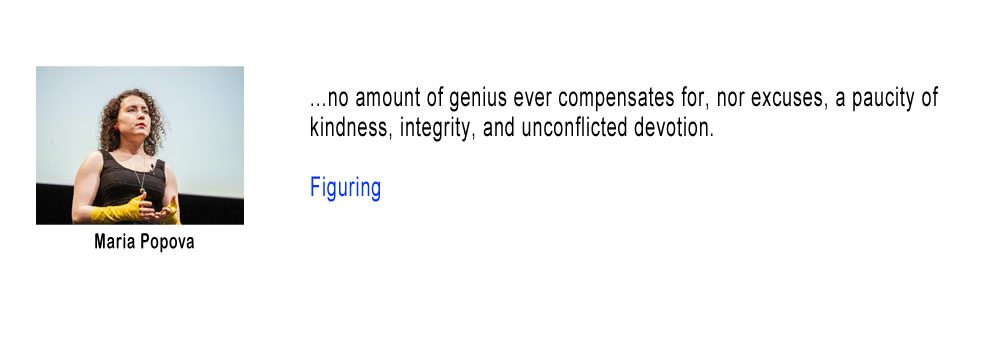
Maria Popova 360x1000
1empireofpain
Spottswood William Robinson 360x1000
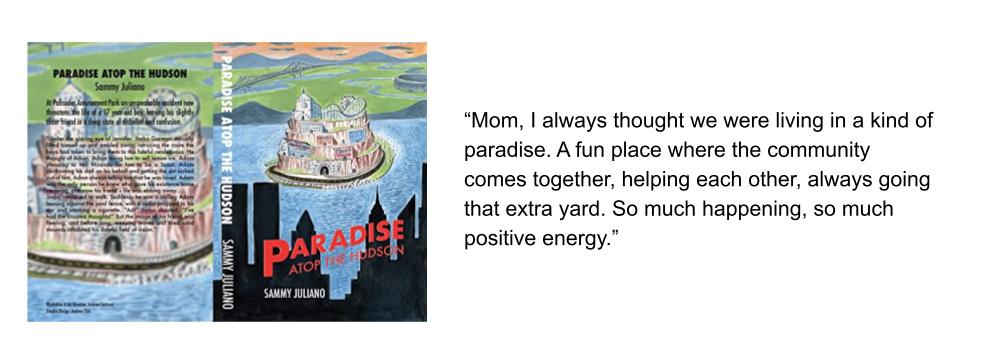
3paradise
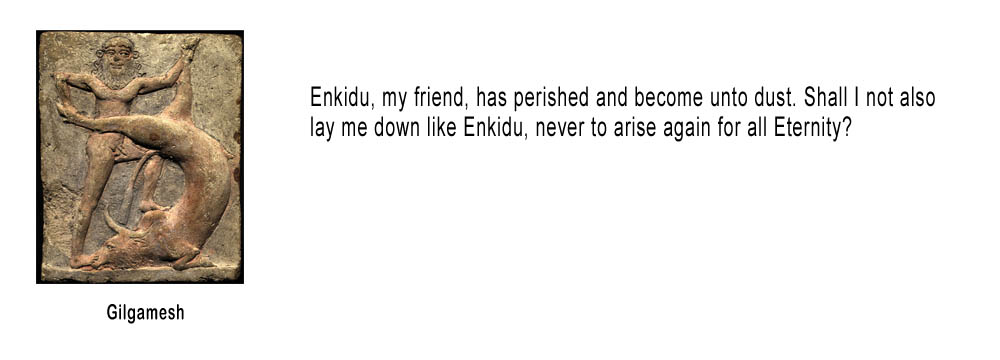
Gilgamesh 360x1000
1jesusandjohnwayne
1confidencegames
2gucci
Learned Hand 360x1000
399
AlexRosenberg
lifeinmiddlemarch2
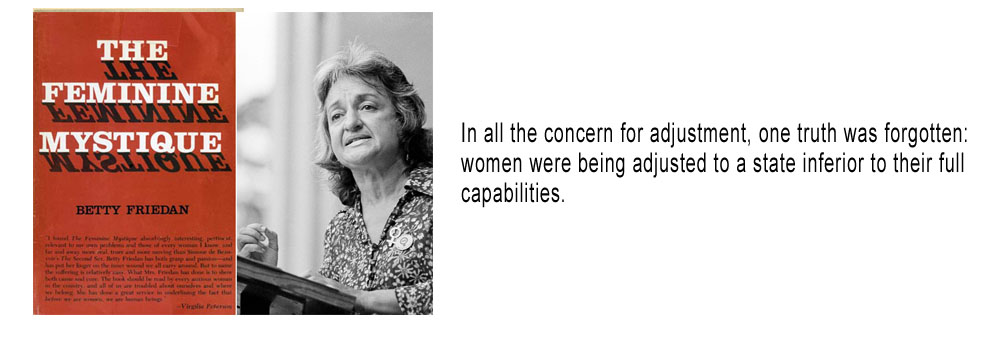
Betty Friedan 360x1000
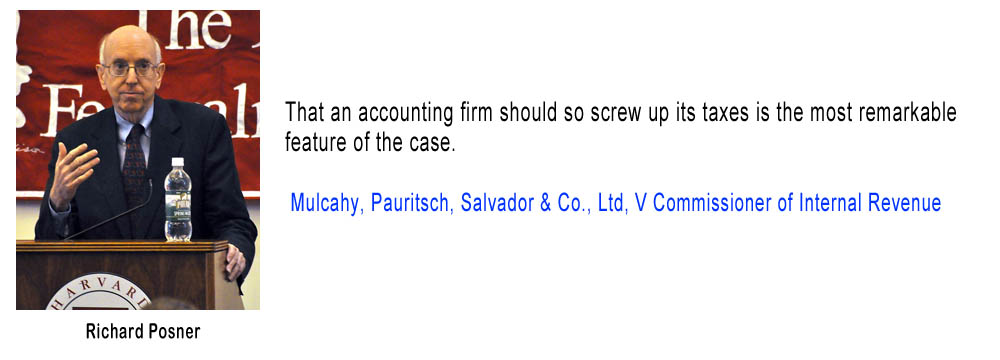
Richard Posner 360x1000
Maurice B Foley 360x1000
Edmund Burke 360x1000
Storyparadox1
Samuel Johnson 360x1000
5confidencegames
1falsewitness
9albion
7confidencegames
lifeinmiddlemarch1
6confidencegames
1madoff
4albion
1paradide
1albion
James Gould Cozzens 360x1000
1lauber
11albion
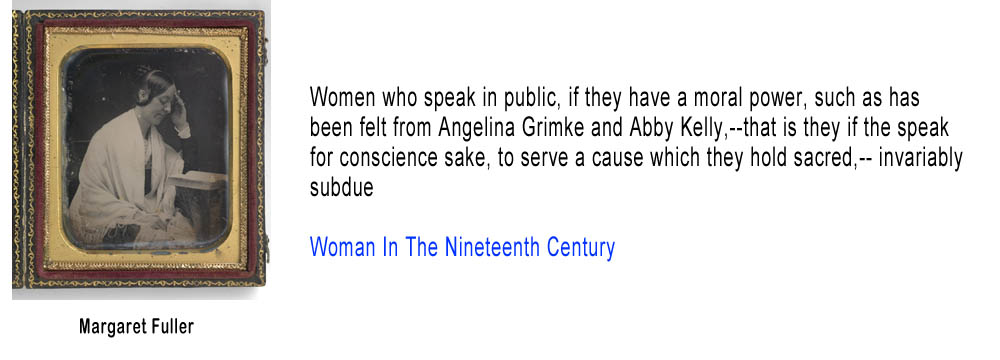
Margaret Fuller1 360x1000
13albion
Office of Chief Counsel 360x1000
2falsewitness
Tad Friend 360x1000
7albion
2lafayette
Thomas Piketty2 360x1000
6albion
2confidencegames
2lookingforthegoodwar
Mark V Holmes 360x1000
3theleastofus
George F Wil...360x1000
10abion
Stormy Daniels 360x1000
Margaret Fuller 360x1000
4confidencegames
1gucci
Ruth Bader Ginsburg 360x1000
Adam Gopnik 360x1000
1transcendentalist
499
Margaret Fuller 2 360x1000
8albion'
3defense
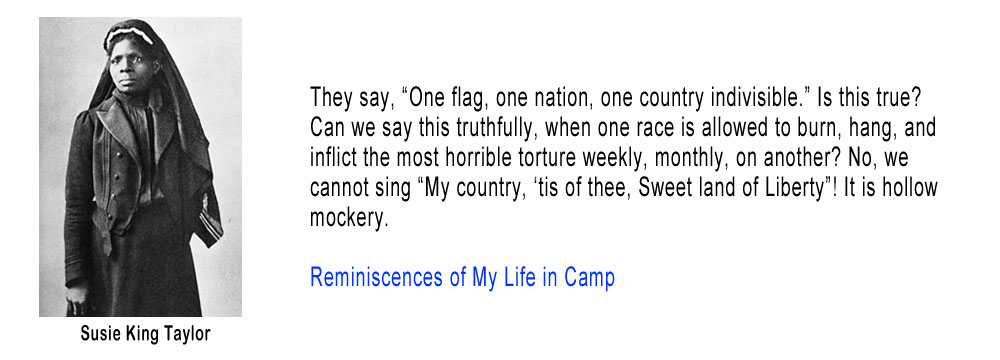
Susie King Taylor 360x1000
Margaret Fuller2 360x1000
1trap
Margaret Fuller4 360x1000
2defense
LillianFaderman
Lafayette and Jefferson 360x1000
2paradise
An Unusual Tax Court Hobby Loss Opinion

An Unusual Tax Court Hobby Loss Opinion

Code Section 183, which does not actually mention hobbies, was part of the Tax Reform Act of 1969.  The IRS issued regulations in 1972.  Both the Code and the Regulations are virtually unchanged since then, so we have nearly 50 years of relevant case law.
read more
Sixth Circuit Rules Low Income Housing Tax Credit Refusal Rights Are Special

Sixth Circuit Rules Low Income Housing Tax Credit Refusal Rights Are Special

Facilitation of the investor exit after the expiration of the fifteen-year compliance period is, therefore, crucial to the efficacy of the LIHTC program. The mechanism creates an incentive, as discussed, for nonprofits to participate in the program; nonprofits will be less likely to enter a partnership that includes an investor, if doing so entails a serious risk of an ownership battle after the fifteenth year. 

read more

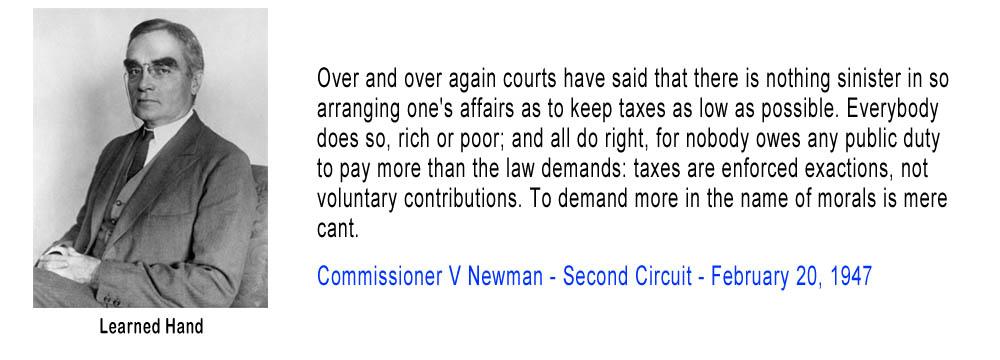
Over and over again courts have said that there is nothing sinister in so arranging one’s affairs as to keep taxes as low as possible. Everybody does so, rich or poor; and all do right, for nobody owes any public duty to pay more than the law demands: taxes are enforced exactions, not voluntary contributions. To demand more in the name of morals is mere cant.