You Should Wear Shoes in Tax Court But Don’t Bring the Box
This was originally published on October 27th, 2010. Thomas F. Hale v. Commissioner, TC Memo 2010-229 Over 500 years ago Fra Luca Bartolomeo de Pacioli published a...
FLP Good for the Family Business – But Maybe not the Family Jewels
The Eighth Circuit affirmed the Tax Court’s conclusion that the restrictions upon the children did not serve a bona fide business purpose because the partnership was not a ““business,” active or otherwise.” Id. at 770. In so holding, the Holman court distinguished a line of cases where active, ongoing business interests were preserved by the transfer restrictions at issue.S
Follow Me
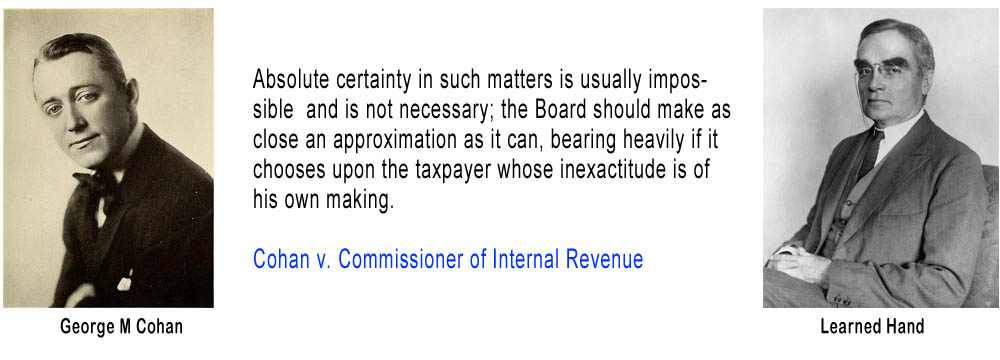
Over and over again courts have said that there is nothing sinister in so arranging one’s affairs as to keep taxes as low as possible. Everybody does so, rich or poor; and all do right, for nobody owes any public duty to pay more than the law demands: taxes are enforced exactions, not voluntary contributions. To demand more in the name of morals is mere cant.