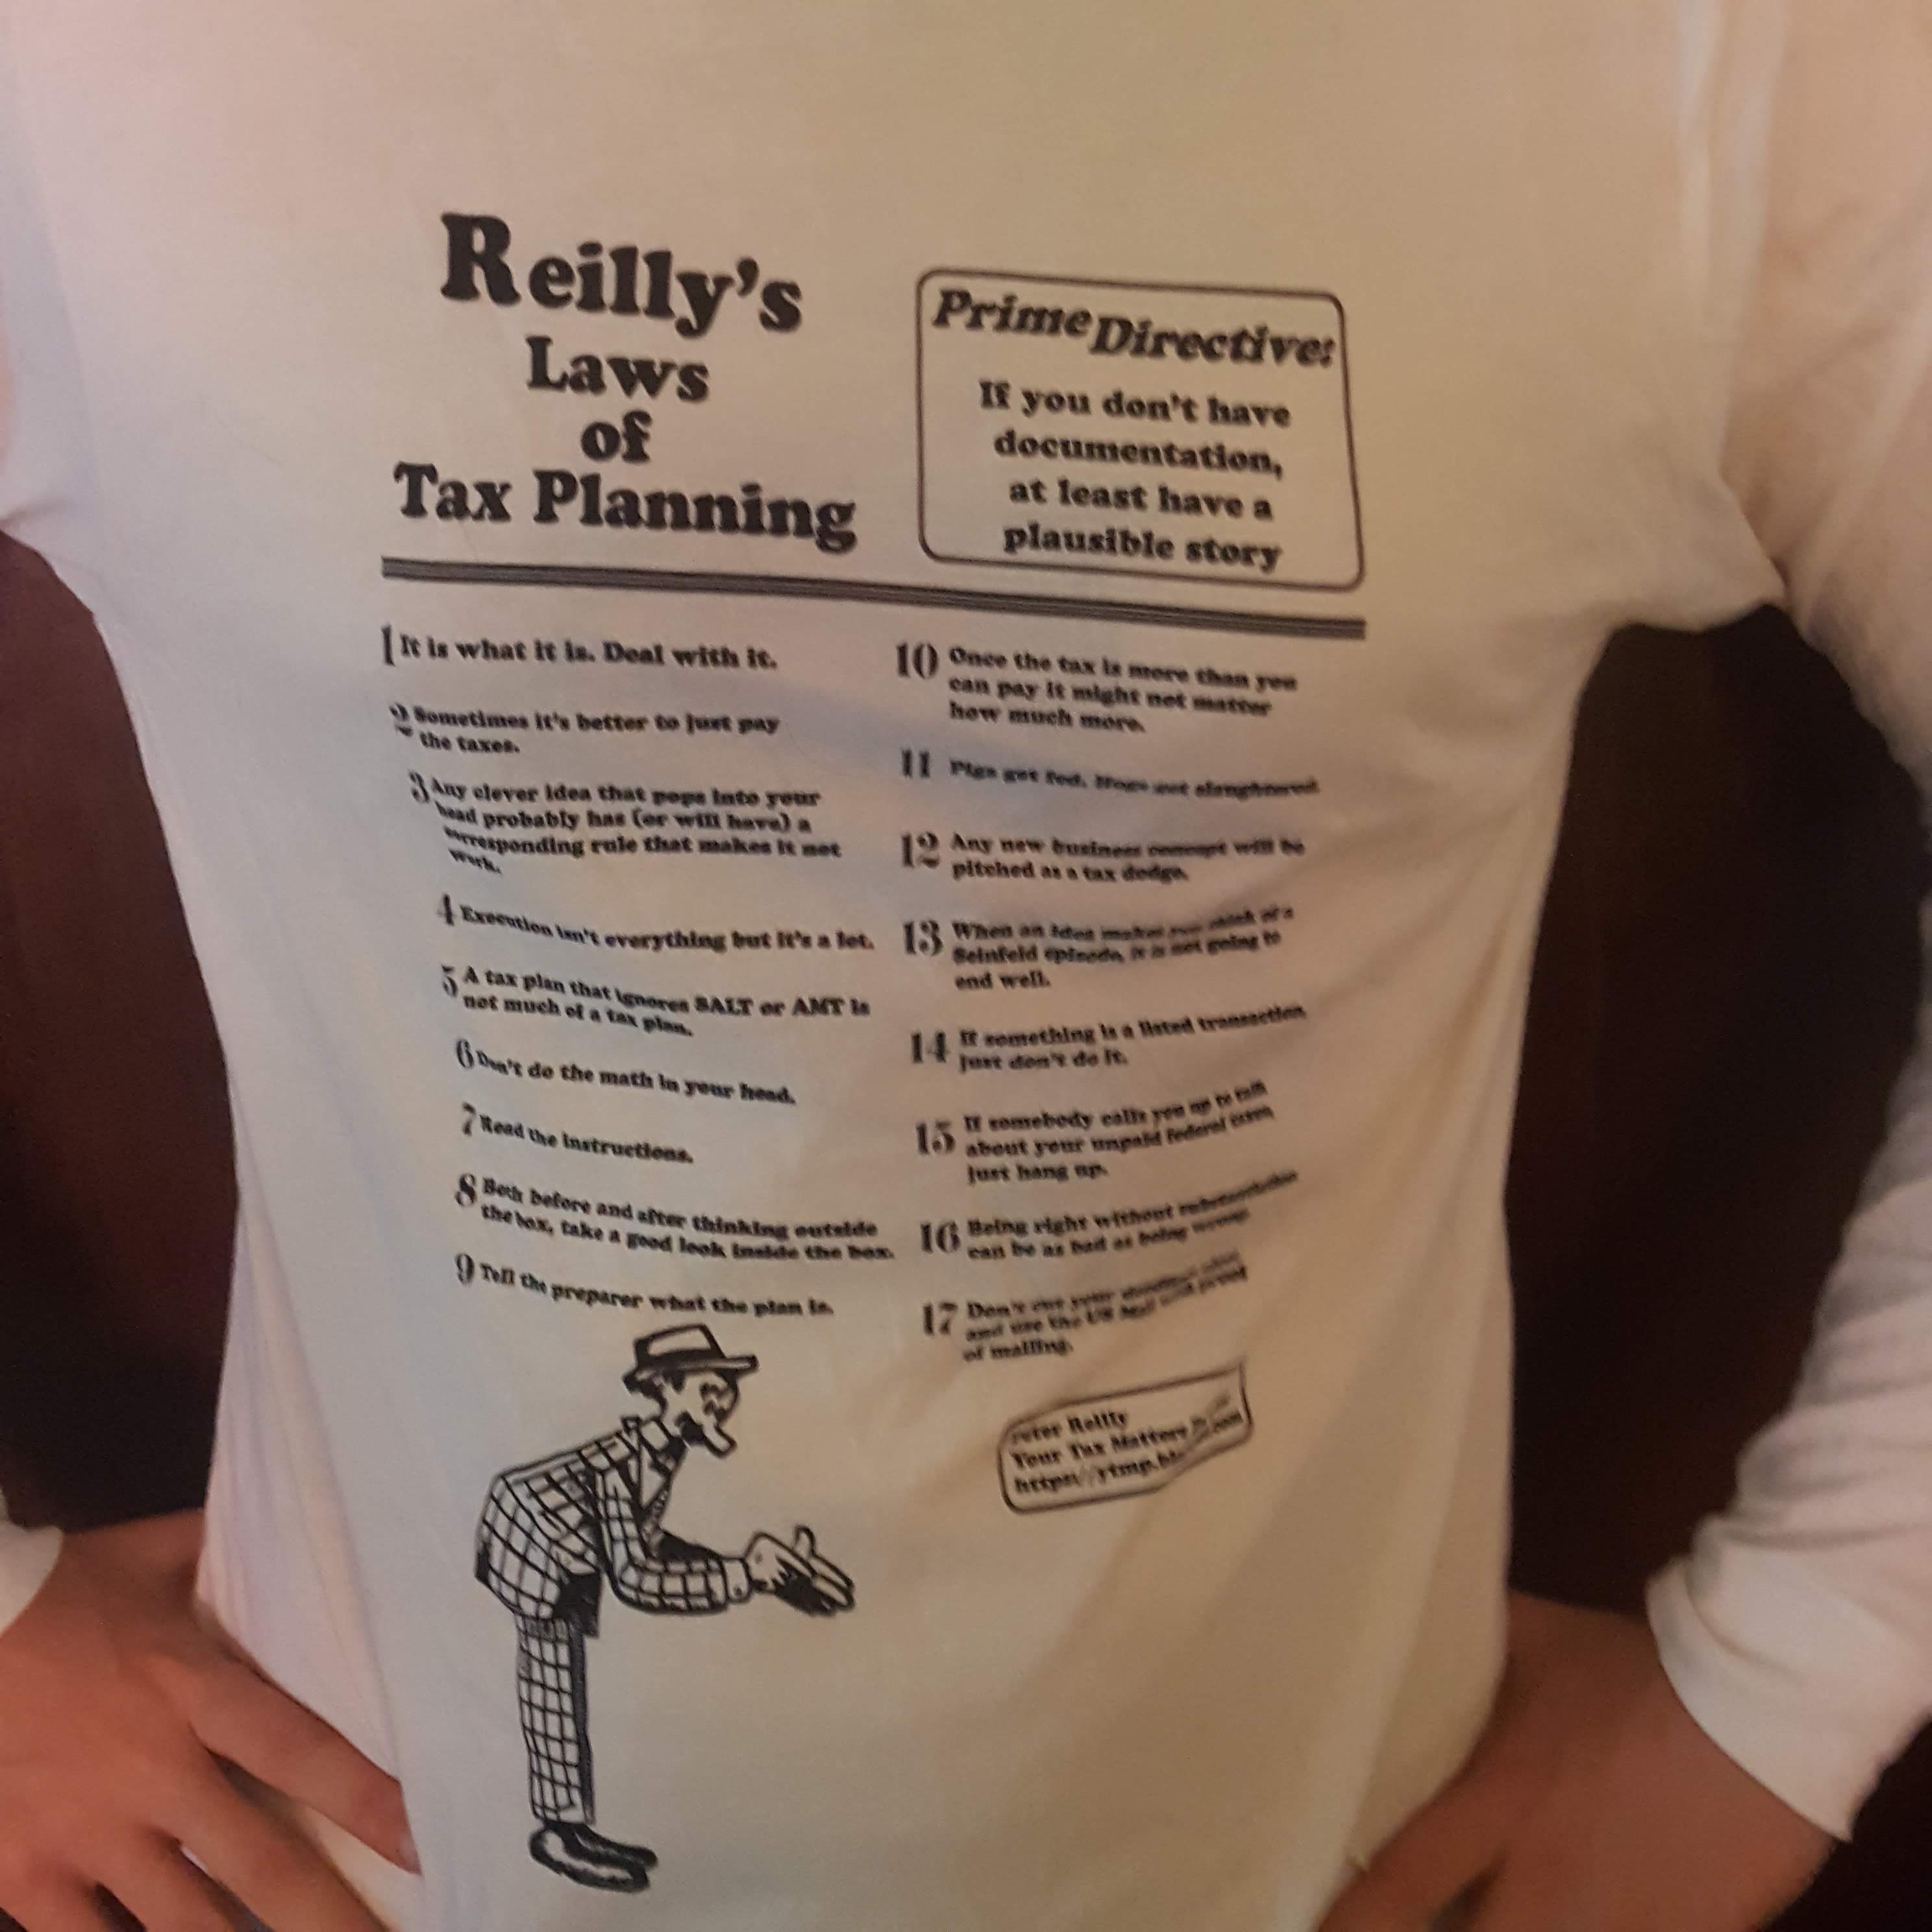
Hobby Loss Roundup And A New Law Of Tax Planning Announced
It is rooted in one of the earliest and most significant 183 decisions, the first time 183 was discussed by an appellate court. It concerned Maurice Dreicer, a trustafarian who spent years (and hundreds of thousands of dollars) searching for the perfect steak. The Second Circuit ruled that the Tax Court had used the wrong standard in denying Dreicer’s losses.
We hold that a taxpayer engages in an activity for profit, within the meaning of Section 183 and the implementing regulations, when profit is actually and honestly his objective though the prospect of achieving it may seem dim. Because the Tax Court applied a different standard, we reverse and remand for redetermination of Dreicer’s deduction claims.
Even on that standard, Dreicer still lost, but that is neither here nor there.
IRS Should Not Be Worrying About Do Not Call Registry
The Tax Court opinion of Judge Daniel Guy in the case of Giving Hearts, Inc. illustrates a waste of IRS resources and focus that is the result of our choice to have the wrong agency regulate not-for-profit organizations. If bad acting by an exempt organization is facilitating significant federal tax avoidance, having the IRS on the case makes a lot of sense. Other abuses of not for profit status should be dealt with by the agency whose business it is to deal with that particular abuse. That’s my takeaway. Here is the story.
Follow Me
Over and over again courts have said that there is nothing sinister in so arranging one’s affairs as to keep taxes as low as possible. Everybody does so, rich or poor; and all do right, for nobody owes any public duty to pay more than the law demands: taxes are enforced exactions, not voluntary contributions. To demand more in the name of morals is mere cant.