Tax Advisers Are Too Afraid Of The Hobby Loss Rules
Section 183 was enacted as part of the Tax Reform Act of 1969. Regulations were issued in 1972. They are mostly unchanged. One of the earlier people to run up against Section 183 was Maurice Dreicer. In 1979, the Tax Court upheld deficiencies totaling $30,000 for 1972 and 1973. (You could call that $180,000 in today’s dollars).
Mr. Dreicer’s “business” was traveling around the world and going to fine restaurants which would endeavor to serve him the”perfect steak”. He was planning a book titled My 27 Year Search for the Perfect Steak — Still Looking. He was already a published author with The Diner’s Companion.
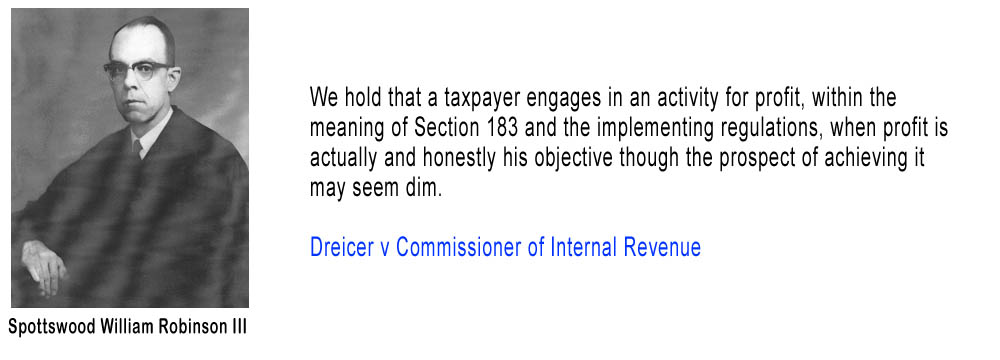
Although it ended up not doing him any good Dreicer’s winning appeal to the DC Circuit set an important precedent.
We perceive no basis for disturbing the Tax Court’s finding on the nature of the undertakings generating the losses for which deductions are sought. We do not accept, however, the legal test that the court employed in ruling on deductibility. We hold that a taxpayer engages in an activity for profit, within the meaning of Section 183 and the implementing regulations, when profit is actually and honestly his objective though the prospect of achieving it may seem dim . Because the Tax Court applied a different standard, we reverse and remand for redetermination of Dreicer’s deduction claims. (Emphasis added)
Denial Of $33M Deduction That Yielded $2M To University Of Michigan Upheld On Appeal
The Tax Court went with zero deduction, but not based on the sham theory. On its own, the Tax Court came up with failure to substantiate based on that missing number on Form 8283. There is something really satisfying with that result. All these smart people with complicated math stuff planning the deal and attacking it and the Tax Court blows it up with what would be a review comment that a senior accountant with three years experience would have given an associate. RTI. (Read the instructions).
Follow Me
Over and over again courts have said that there is nothing sinister in so arranging one’s affairs as to keep taxes as low as possible. Everybody does so, rich or poor; and all do right, for nobody owes any public duty to pay more than the law demands: taxes are enforced exactions, not voluntary contributions. To demand more in the name of morals is mere cant.