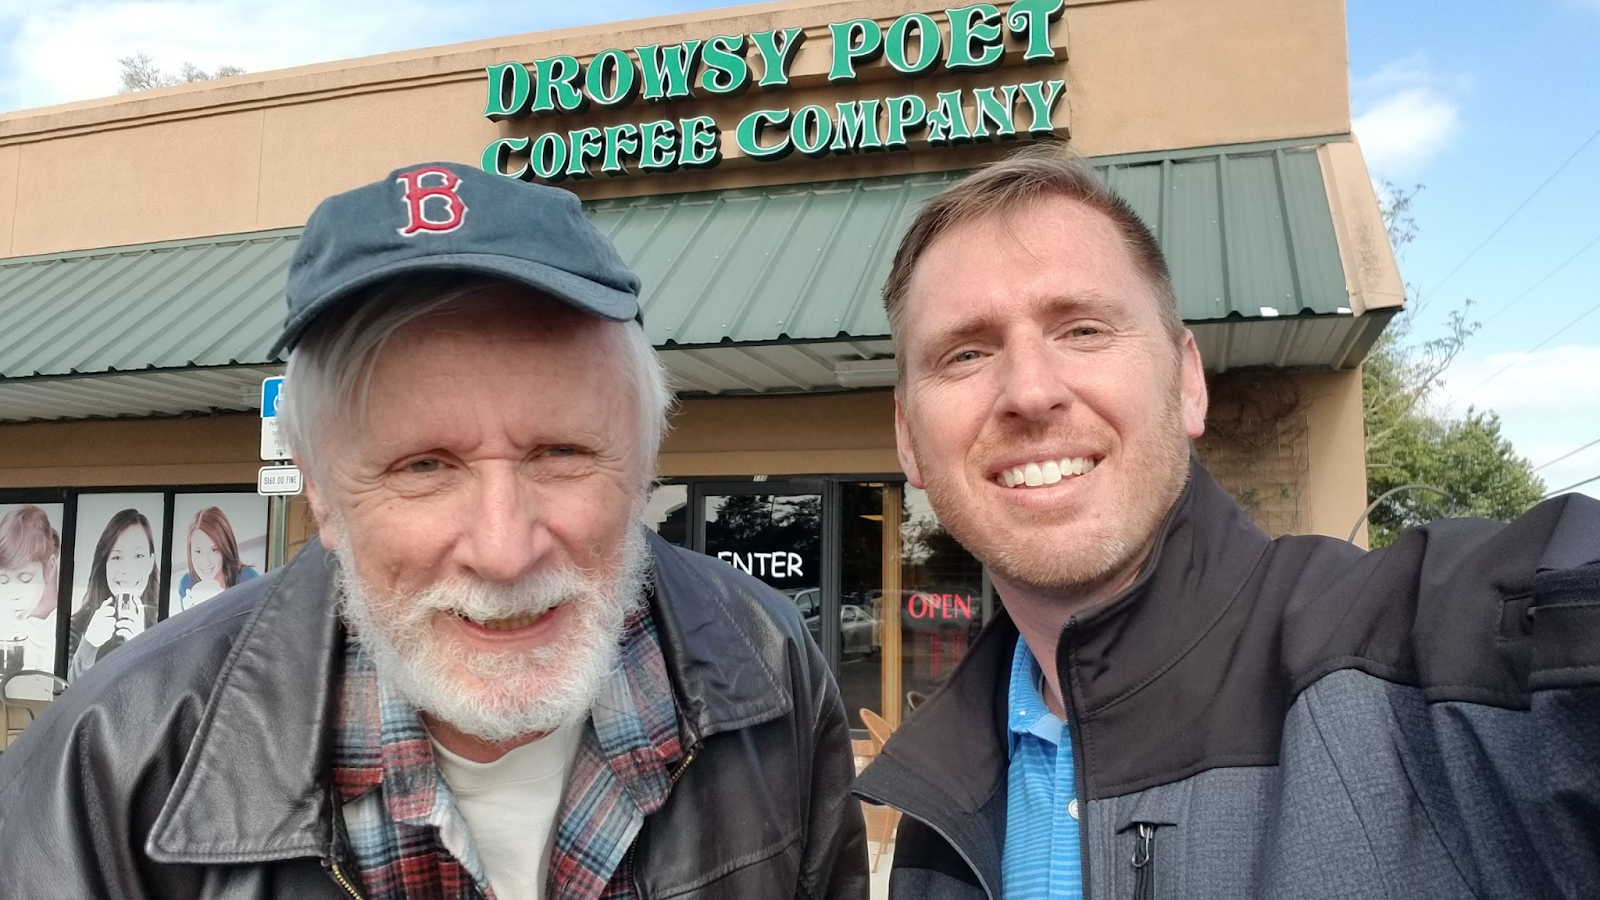
Lunch At The Drowsy Poet With Eric Hovind
I hadn't planned on writing about my get together with Eric Hovind or even telling anybody about it other than my partner. At the end of our time together, though, he...
Seventh Circuit Blesses Tax Free Housing Payments To Clergy
Although I will be studying the decision more, I think it is fair to say that the reasoning of Professor Edward Zelinsky author of Taxing The Church carried the day. The Court viewed 107(2) as just one of a myriad of provisions exempting housing. To treat ministers like secular employees receiving the 119(a) convenience of the employer exemption might lead to intrusive inquiries. This is weighed against the IRS having to patrol the boundary of who is a minister.
These parallel provisions show an overarching arrangement in the tax code to exempt employer-provided housing for employees with certain job-related housing requirements. Congress has exempted certain categories of employees from complying with the specific requirements of § 119(a)(2) to simplify the application of the convenience-of-the-employer doctrine to those occupations. Section 107, including subsection (2), recognizes ministers often use their homes as part of their ministry. This provision thus eases the administration of the convenience-of-the-employer doctrine by providing a bright-line rule, instead of requiring that ministers and the IRS repeatedly engage with a fact-intensive standard.
Follow Me
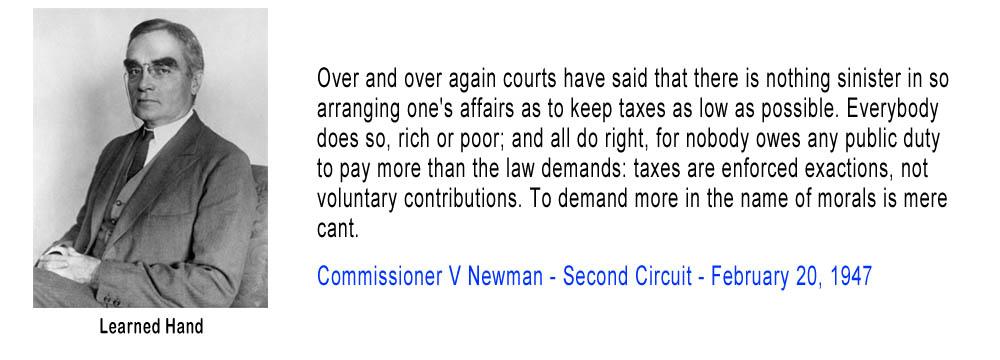
Over and over again courts have said that there is nothing sinister in so arranging one’s affairs as to keep taxes as low as possible. Everybody does so, rich or poor; and all do right, for nobody owes any public duty to pay more than the law demands: taxes are enforced exactions, not voluntary contributions. To demand more in the name of morals is mere cant.