Billionaire Bruins Owner Beats IRS On Tax Deductions For Away Game Meals
Since the whole away team crew is away from its business home, the IRS does not question that the meals are deductible. Generally, though, the deduction for meals is limited to 50% (Code Section 274(n)). There are exceptions. There were two that the Bruins owners argued they qualified for. One was that the meals were a “de minimis” fringe benefit and the other was that they were an expense of entertainment sold to customers. The first excuse turned out to be good enough, so the Tax Court did not discuss the second one.
It might seem odd, but a footnote indicates that the IRS was not proposing an adjustment with respect to meals provided to players and staff in TD Gardens in Boston, but that is the key to the controversy.
In order to qualify as de minimis fringe benefits the meals must be provided in a non-discriminatory manner. There did not seem to be any issue about that. The more challenging requirement is that the meals be provided at a facility owned or leased by the employer located on or near the business premises of the employer. That’s why there was no question about meals provided for home games
Scholar Goes To Rest With Margaret Fuller
Some stuff you just can't make up and the final chapter, perhaps the epilogue, in the life of Marie Olesen Urbanski Whittaker is like that. This being my blog and all,...
Follow Me
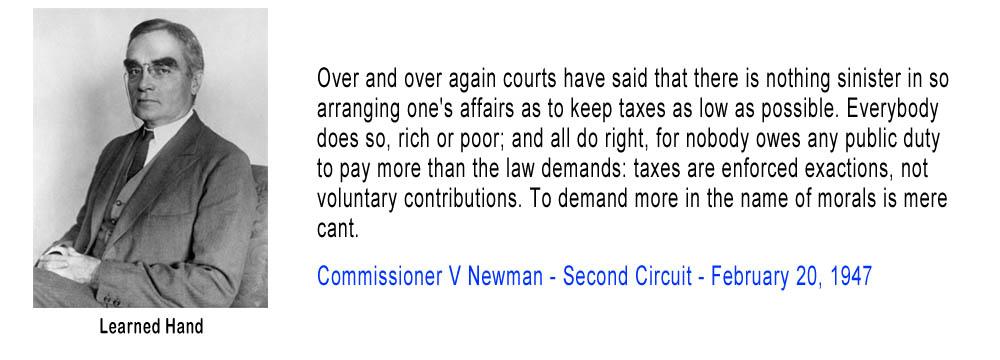
Over and over again courts have said that there is nothing sinister in so arranging one’s affairs as to keep taxes as low as possible. Everybody does so, rich or poor; and all do right, for nobody owes any public duty to pay more than the law demands: taxes are enforced exactions, not voluntary contributions. To demand more in the name of morals is mere cant.