Divorce Has Tax Traps – Get Some Advice
Petitioner’s argument that the transfer of $80,000 (the fair market value of the Sweet Briar property) was deductible as an alimony payment fails because it was not a payment in cash. Instead the transfer was a transfer of property and therefore does not constitute an alimony payment. Although petitioner and Mr. Williams agreed that petitioner’s transfer of the Sweet Briar property would replace $80,000 of petitioner’s alimony obligation, the intent of the parties does not determine the deductibility of a payment as alimony under section 71. See Okerson v. Commissioner, 123 T.C. 258, 264-265 (2004). Instead the test for [*7] whether a payment is deductible as alimony is a straightforward, objective test that rests entirely on the fulfillment of explicit requirements set forth in section 71, including that the payment be made in cash or a cash equivalent.
IRS Defends Its Policy Of Not Penalizing Small Errors
The big argument between TIGTA and IRS is on the negligence penalty. TIGTA being a bunch of hard-assed internal auditors figures that if somebody omits income they were negligent – end of story. (Remember the negligence penalty is for the misstatements that misstate the tax by less than 10%). The programmatic approach of AUP is to let people off with a warning the first time. Thus the for the lower understatements a negligence penalty is only proposed for “repeaters” i.e. somebody who has previously been dinged in the last four years. TIGTA does not think there is any support for this easy going approach.
Follow Me
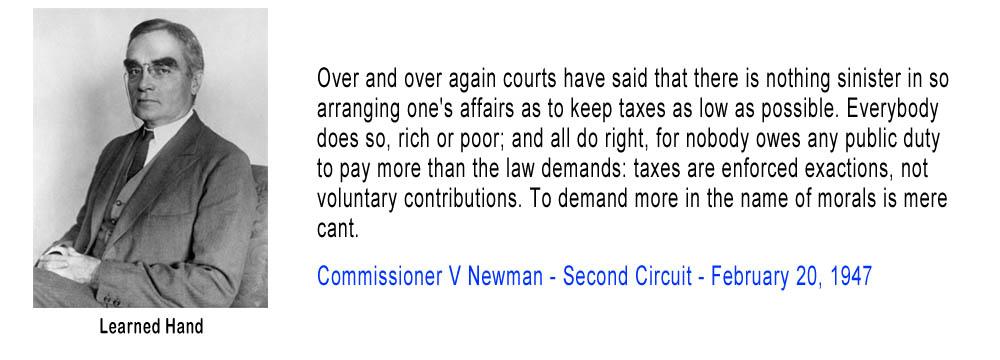
Over and over again courts have said that there is nothing sinister in so arranging one’s affairs as to keep taxes as low as possible. Everybody does so, rich or poor; and all do right, for nobody owes any public duty to pay more than the law demands: taxes are enforced exactions, not voluntary contributions. To demand more in the name of morals is mere cant.