IRS Forced To Release Names Of Targeted Groups
The paper identifies the ill-conceived massive 1998 structural reorganization and division (like salami-slicing) of field operations as a major cause of the IRS’s current legal battles and “downward slide.” In its 1998 aftermath, we were all left with an overly centralized Washington IRS National Office and an undermanaged array of field operations. That’s where the Tea Party scandal started; and, even more importantly, it need never be repeated. Indeed, such events must stop!
“With that recognition, change-makers can travel a 2015 bipartisan pathway to addressing a wrong-headed 1998 “solution” to a 1998 non-existent structural problem by introducing a 2015 proposal for a National Office consolidation (slimming down) coupled with a field operations decentralization (closer to customers and ending the practice of absentee senior management without local accountability).
Minority Shareholders Liable For Part Of Corporate Income Tax
The corporate veil exists to protect shareholders from actions taken against the corporation. However, as is seen in Kardash, this protection is not unlimited. Proper capitalization and record keeping, segregation of corporate and personal assets, and following corporate formalities are all requirements necessary to protect the veil. Where significant undercapitalization is present, specifically undercapitalization caused by fraud, the protections afforded by the veil are pierced exposing the shareholders to liability. Taxpayers should take note of the decision in Kardash as it serves as a reminder to respect the separate and distinct nature of the corporate entity.
Follow Me
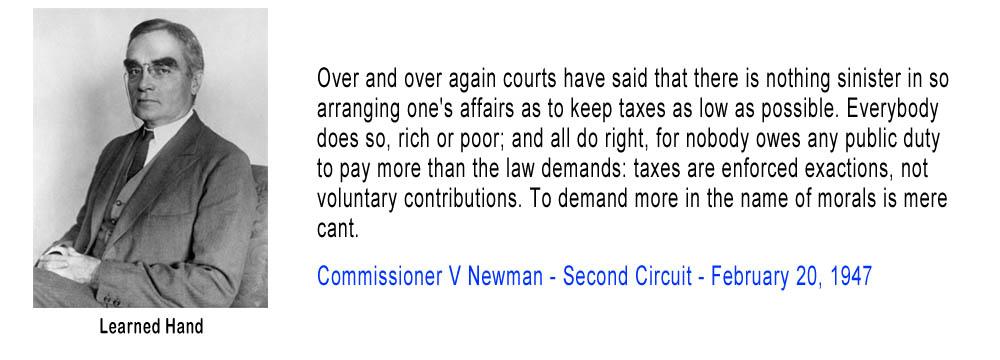
Over and over again courts have said that there is nothing sinister in so arranging one’s affairs as to keep taxes as low as possible. Everybody does so, rich or poor; and all do right, for nobody owes any public duty to pay more than the law demands: taxes are enforced exactions, not voluntary contributions. To demand more in the name of morals is mere cant.