Kent Hovind Trials – Final Round Of The First Fight – Installment One
In mid March as I struggled with corporate extensions and continued wrestling with the tangible property regulations, my friend, filmmaker Jonathan Schwartz was in...
IRS Agent Causes Grief For Taxpayer’s Spouse By Being Helpful
Generally, pursuant to section 6011(a) a taxpayer obligated to file a Federal tax return must conform to the forms and regulations prescribed by respondent. Even though signed by petitioner and Mr. Rodriguez, the consent is hardly a form described in section 6011 or section 1.6011-1, Income Tax Regs. Furthermore, a Form 4549 is not signed by the taxpayer under penalties of perjury, one of the critical requirements for a document to be treated as a Federal income tax return. Petitioner’s argument that the consent should be treated as a joint return is rejected.
Follow Me
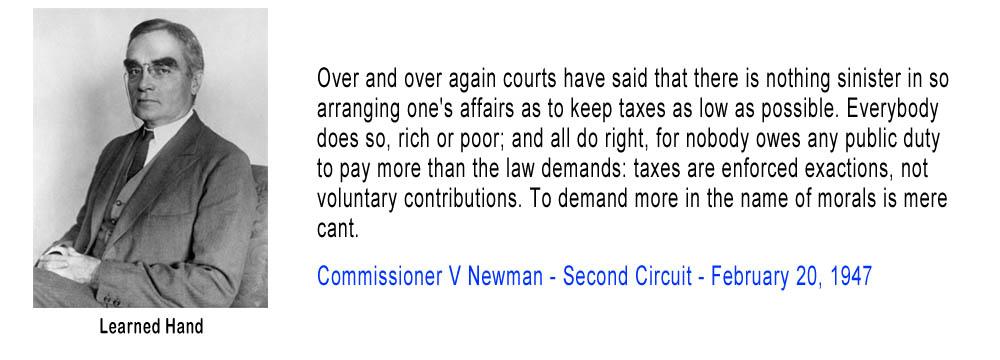
Over and over again courts have said that there is nothing sinister in so arranging one’s affairs as to keep taxes as low as possible. Everybody does so, rich or poor; and all do right, for nobody owes any public duty to pay more than the law demands: taxes are enforced exactions, not voluntary contributions. To demand more in the name of morals is mere cant.