Thomas Piketty2 360x1000
AlexRosenberg
Samuel Johnson 360x1000
3albion
Thomas Piketty1 360x1000
2falsewitness
Storyparadox1
7albion
2transadentilist
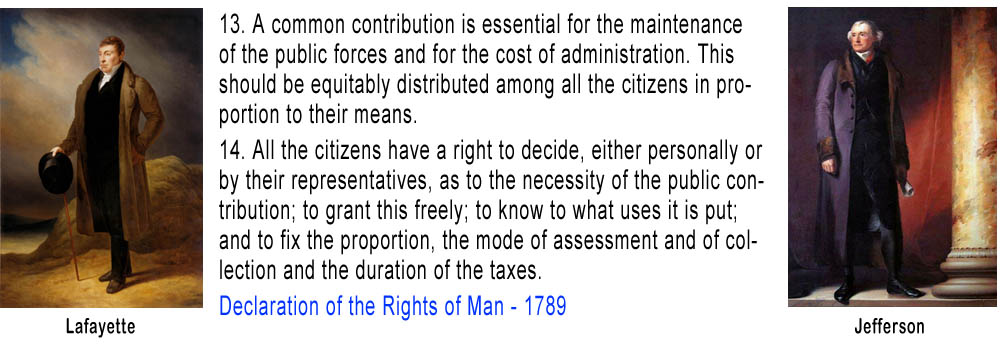
Lafayette and Jefferson 360x1000
1defense
Mark V Holmes 360x1000
5confidencegames
LillianFaderman
Thomas Piketty3 360x1000
Adam Gopnik 360x1000
Tad Friend 360x1000
Brendan Beehan 360x1000
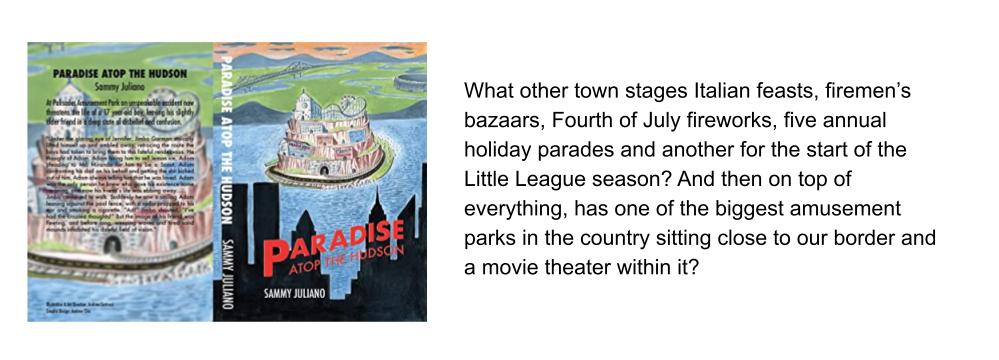
2paradise
5albion
Learned Hand 360x1000
Margaret Fuller4 360x1000
4confidencegames
2lafayette
4albion
1falsewitness
lifeinmiddlemarch1
1transcendentalist
Edmund Burke 360x1000
George M Cohan and Lerarned Hand 360x1000
299
399
199
storyparadox3
3paradise
14albion
11albion
2gucci
lifeinmiddlemarch2
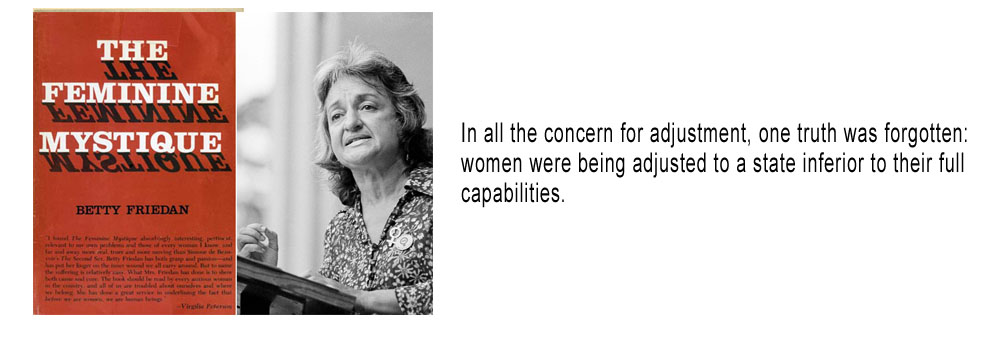
Betty Friedan 360x1000
Margaret Fuller2 360x1000
1lookingforthegoodwar
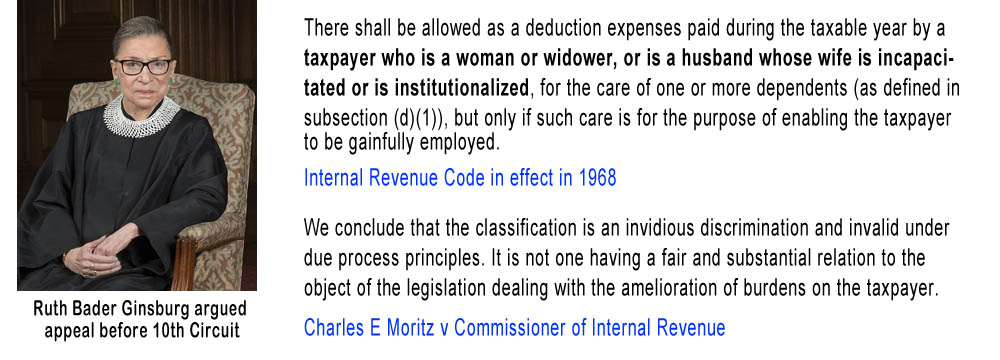
Ruth Bader Ginsburg 360x1000
Margaret Fuller5 360x1000
1madoff
3theleastofus
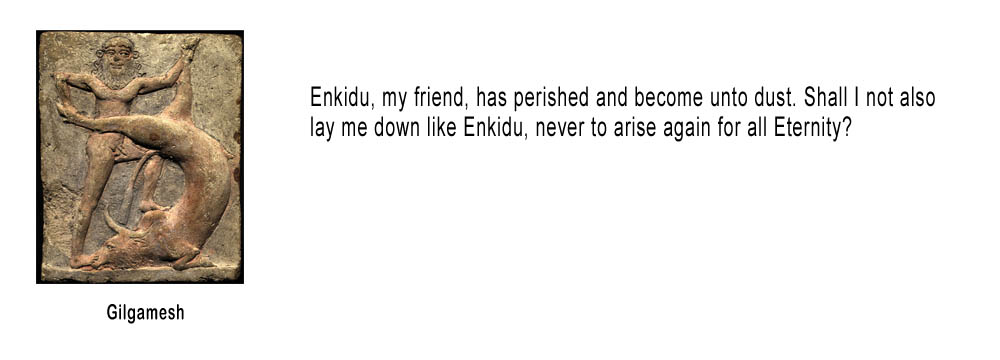
Gilgamesh 360x1000
Margaret Fuller 2 360x1000
Maurice B Foley 360x1000
1empireofpain
storyparadox2
12albion
7confidencegames
3defense
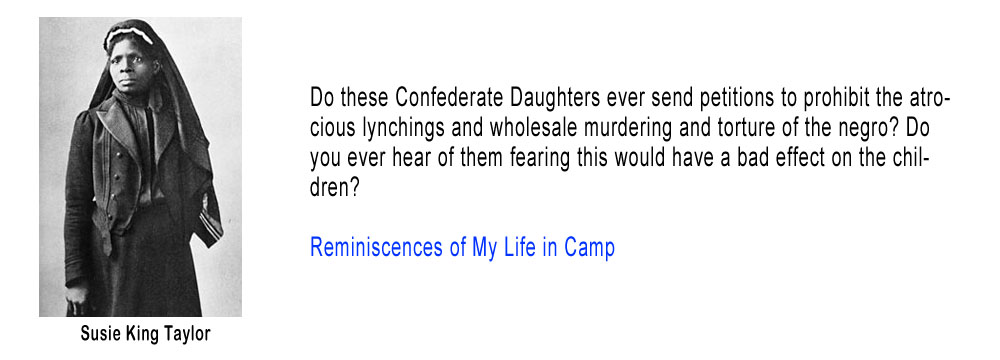
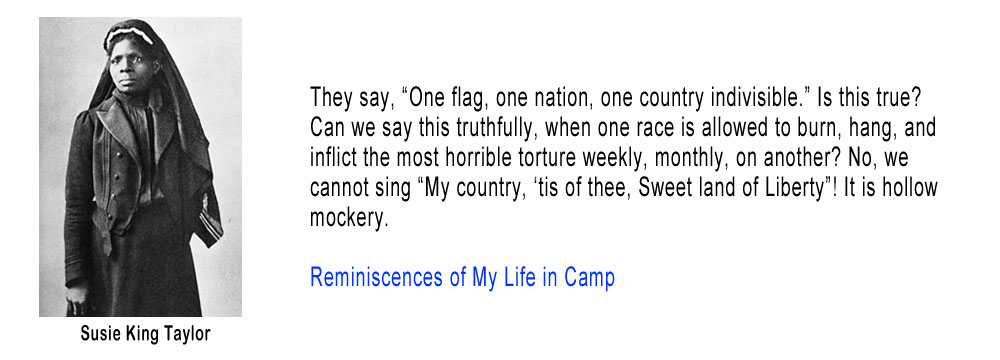
Susie King Taylor2 360x1000
Office of Chief Counsel 360x1000
6albion
Margaret Fuller3 360x1000
2confidencegames
Anthony McCann1 360x1000
9albion
Susie King Taylor 360x1000
2lookingforthegoodwar
6confidencegames
1lauber
James Gould Cozzens 360x1000
1trap
499
Spottswood William Robinson 360x1000
Margaret Fuller1 360x1000
Richard Posner 360x1000
1gucci
2albion
2trap
8albion'
1theleasofus
1confidencegames
Stormy Daniels 360x1000
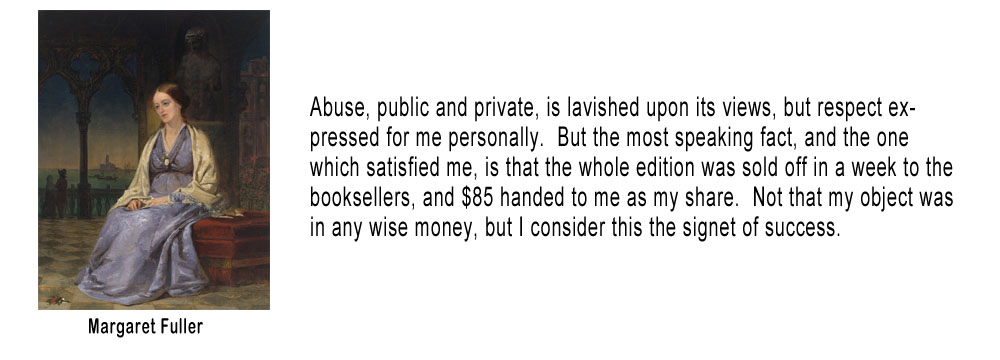
Margaret Fuller 360x1000
1albion
1lafayette
13albion
2theleastofus
3confidencegames
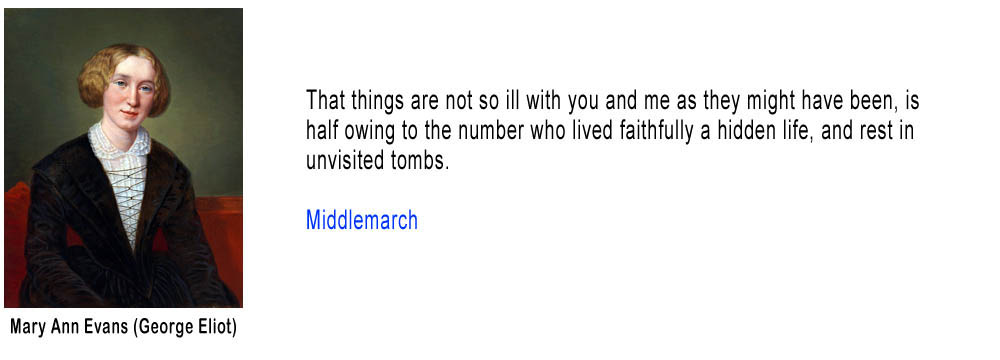
Mary Ann Evans 360x1000
11632
Maria Popova 360x1000
1paradide
2defense
George F Wil...360x1000
Anthony McCann2 360x1000
2jesusandjohnwayne
1jesusandjohnwayne
10abion
IRS Agent Causes Grief For Taxpayer’s Spouse By Being Helpful

IRS Agent Causes Grief For Taxpayer’s Spouse By Being Helpful

Generally, pursuant to section 6011(a) a taxpayer obligated to file a Federal tax return must conform to the forms and regulations prescribed by respondent. Even though signed by petitioner and Mr. Rodriguez, the consent is hardly a form described in section 6011 or section 1.6011-1, Income Tax Regs. Furthermore, a Form 4549 is not signed by the taxpayer under penalties of perjury, one of the critical requirements for a document to be treated as a Federal income tax return.  Petitioner’s argument that the consent should be treated as a joint return is rejected.

read more

Over and over again courts have said that there is nothing sinister in so arranging one’s affairs as to keep taxes as low as possible. Everybody does so, rich or poor; and all do right, for nobody owes any public duty to pay more than the law demands: taxes are enforced exactions, not voluntary contributions. To demand more in the name of morals is mere cant.