James Traficant Jr. And The Taxpayer’s Burden
Mr. Traficant’s place in tax history is fairly solid, as the Sixth Circuit decision has been cited dozens of time since it was issued. Most recent was the case of Pitcher v Waldman in which Traficant was cited for the principle that fraud can be inferred from circumstantial evidence. I was surprised that I missed Pitcher v Waldman when it came out in early April since it concerned the ugly breakup of a CPA firm. I was thinking I need to do a late post on it, but it turns out that Joe Kristan covered it quite well.
Nevada High Court OKs Tax That Hits Strip Clubs, Exempts NASCAR And Boxing
The other argument is that because of the various exceptions such as boxing and NASCAR there is a discrimination between adult-oriented entertainment and family-oriented entertainment. It’s worth noting that there is something a little off about a culture that thinks it is OK for children to see people beating up on one another and crashing cars but not, post infancy anyway, female breasts. Nonetheless, maybe the clubs have something of an argument there, since “It is what it is”.
In analyzing the claim, the Court notes that the clubs are not starting off from real solid ground.
Follow Me
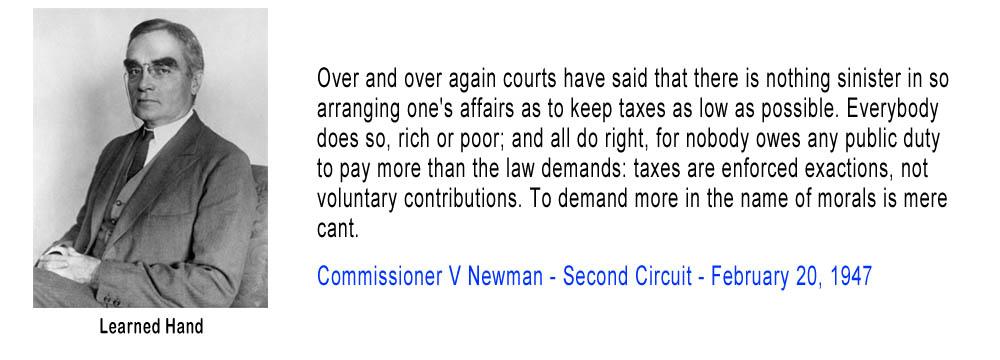
Over and over again courts have said that there is nothing sinister in so arranging one’s affairs as to keep taxes as low as possible. Everybody does so, rich or poor; and all do right, for nobody owes any public duty to pay more than the law demands: taxes are enforced exactions, not voluntary contributions. To demand more in the name of morals is mere cant.