Professional C Corp Denied Deduction For Uncashed Salary Check To Owner
When I think of the simple things that might have avoided this problem, it makes me want to cry. Mr. Vanney indicates that the corporation could have easily borrowed the money. So how much would a $200,000 loan for a month or two have cost? Considerably less than over a quarter of a million dollars in corporate tax. Alternatively, he could have taken a $400,000 bonus in early December, cashed the check and made a formal documented loan to the company. Then there would have been enough cash to pay out the balance at the end of December.
There is even a last minute solution that occurs to me. Instead of cutting a net check for $460,000, make the net check for $250,000 which is deposited in Mr. Vanney’s account to be loaned back if necessary in January. For the balance of the net pay instead of just making a book entry, have the corporation issue a negotiable promissory note. Even if the negotiable promissory note, which I think should work, does not stand up, at least, most of the deduction is safe.
Need To Show Rental Effort To Deduct Expenses
As the Tax Court noted, evidence the Meinhardts made no changes in their efforts to rent the property, despite thirty unsuccessful years, undermined their assertion that they sought to profit by renting the property. The lack of evidence of a rental property business strategy, and evidence they allowed relatives to live in the house rent-free, supported a finding that the Meinhardts held the property as an alternative residence for the personal use of their extended family.
Follow Me
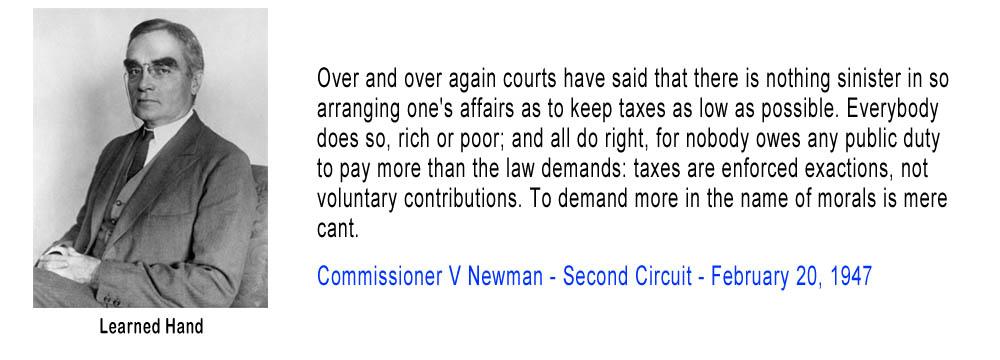
Over and over again courts have said that there is nothing sinister in so arranging one’s affairs as to keep taxes as low as possible. Everybody does so, rich or poor; and all do right, for nobody owes any public duty to pay more than the law demands: taxes are enforced exactions, not voluntary contributions. To demand more in the name of morals is mere cant.