IRS Stampedes A Cattle Shelter
Interestingly, in attacking Mr. Gardner’s cattle activity, the IRS passed over both the silver bullet and the stiletto to go for the blunt instrument – Section 183. Section 183 is sometimes called the “hobby loss section”, but its application is much broader. Basically, if you post losses from an activity in which you are not trying to make a profit you can be denied those losses under Section 183. It is much worse than having the losses deferred under the passive activity loss rules. It may turn out to be even much, much worse than having the losses suspended under the at-risk rules, but we will save that for the end.
For Property Tax Exemption Culture Not As Good As Charity
It is difficult to find a clear element of charity in Plaintiff’s stated purpose. Photography education and public awareness are culturally enriching, but not necessarily charitable. Plaintiff has a building with a gallery that displays photography, classrooms for photography classes, darkrooms, and digital photography laboratories. The public is free to stroll through the gallery looking at pictures on the walls and attend several lectures each year free of charge. However, photography classes are taught for a fee and the public must pay to use Plaintiff’s photography laboratories, darkrooms, and studio….
Follow Me
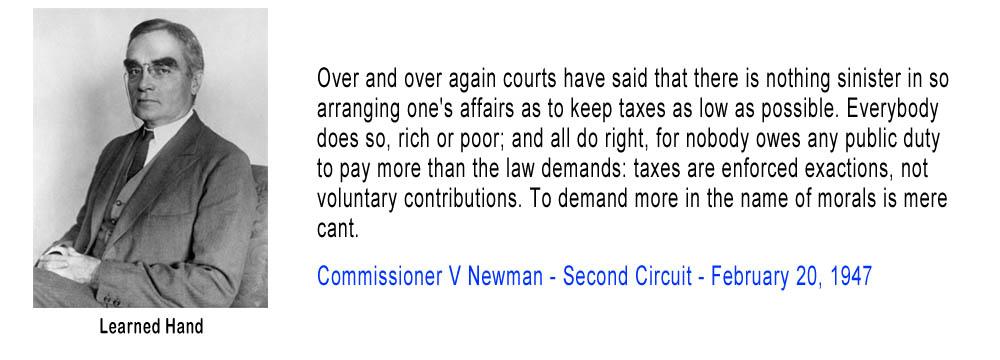
Over and over again courts have said that there is nothing sinister in so arranging one’s affairs as to keep taxes as low as possible. Everybody does so, rich or poor; and all do right, for nobody owes any public duty to pay more than the law demands: taxes are enforced exactions, not voluntary contributions. To demand more in the name of morals is mere cant.