Alimony Deduction Requires Good Substantiation
But it gets more complicated. There was a $63,500 check that was included in the substantiation of a total alimony deduction of $90,265.67. The check was issued eight days after the required property settlement. “Spousal Support” was written in the memo section of the check, but that was crossed out.
Mr. Peery argued that the property settlement had been paid from other sources and that the $63,500 check was his ex-wife’s share of a capital gain. Just one of those crazy coincidences. It happens. Unfortunately, he was unable to substantiate the other $63,500, leaving the IRS unsatisfied and the Tax Court agreeing, The Court also upheld the accuracy penalty.
Connecticut Limits $60 Million NOL Carryback
Recognizing that Connecticut individual state income taxes are a creature of statute, see § 12-700 et seq., the lack of statutory authority to deduct NOLs arrived at under federal tax laws, precludes the plaintiffs from deducting NOLs from CAGI rather than federal taxable income. NOLs were created under federal tax laws to deal with excess business losses used to offset positive income years arrived at under federal tax laws. Federal tax laws provide for the limitation on the use of NOLs to taxable income rather than AGI. This is more in line with the application of federal tax concepts to Connecticut tax laws. Considering all of the factors in this case, the only conclusion for the court to arrive at is that the plaintiffs are limited to applying their federal NOLs to federal taxable income rather than to CAGI, which is, in fact, federal AGI.
Follow Me
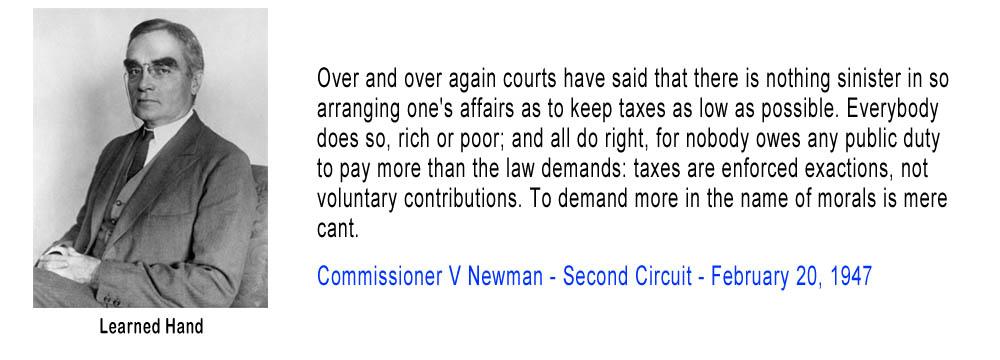
Over and over again courts have said that there is nothing sinister in so arranging one’s affairs as to keep taxes as low as possible. Everybody does so, rich or poor; and all do right, for nobody owes any public duty to pay more than the law demands: taxes are enforced exactions, not voluntary contributions. To demand more in the name of morals is mere cant.