IRS Chief Counsel Checks 1986 Committee Reports To Give Break On Foreclosed Real Estate
A foreclosure on real property subject to recourse debt comprising the taxpayer’s entire interest in a passive (or former passive) activity is a fully taxable transaction for purposes of §§ 1001 and 469(g)(1)(A), regardless of whether any COD income from the cancellation of recourse debt is excluded under § 108(a)(1)(B). Thus, the losses from the activity are treated as not from a passive activity under §469(g)(1)(A). Additionally, these losses are not reduced by any excluded COD income under § 108(b)(2)(F).
Kicking The Jesuits Out Of California – Some Quirky Artwork Documenting California History
According to wikipedia By 1767, Jesuit missionaries on the peninsula of Baja California had established approximately 23 missions over a period of 72 years. Rumors were...
Follow Me
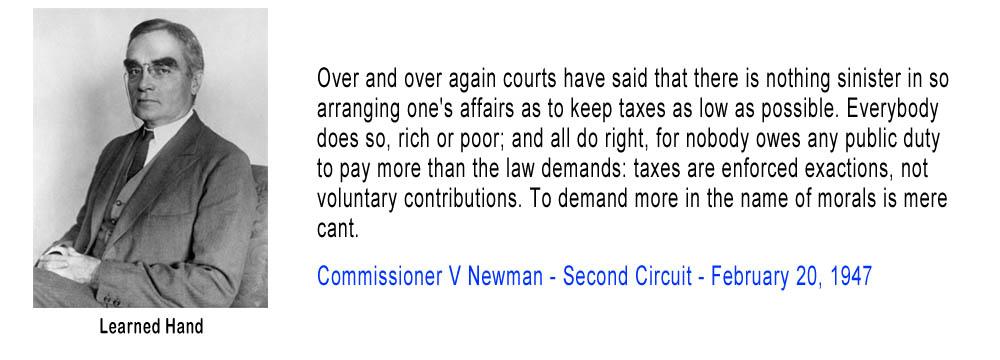
Over and over again courts have said that there is nothing sinister in so arranging one’s affairs as to keep taxes as low as possible. Everybody does so, rich or poor; and all do right, for nobody owes any public duty to pay more than the law demands: taxes are enforced exactions, not voluntary contributions. To demand more in the name of morals is mere cant.