Nonrecognition On Divorce Transfers Hurts Receiving Spouse
We understand petitioner to argue that she had reasonable cause for treating the Distribution as nontaxable income because she contends that she relied in good faith on the advice of her tax professional. Petitioner’s assertion is unsubstantiated. Petitioner did not demonstrate that a tax professional advised her to take the position that the Distribution was nontaxable income. Petitioner’s inclusion of an unauthenticated and unsigned document, purportedly created by her tax professional, does not substantiate her claim. Moreover, there is nothing in the record regarding whether the Distribution was nontaxable income. Additionally, there is nothing in the record demonstrating that petitioner provided the Form 1099-R to her tax professional.
IRS Cannot Levy Tribal Payments
It is not just the tribes that make per-capita payments. The State of Alaska also makes a distribution to all its residents, although it is much more modest than what the Puyallup pay. If you go back to the Founders, you will find that Thomas Paine advocated some sort of per-capita payment to recognize that unlike the state of nature where there were lots of things available if you were willing to do a bit of work, even by the late eighteenth century most of the world was owned by somebody.
Follow Me
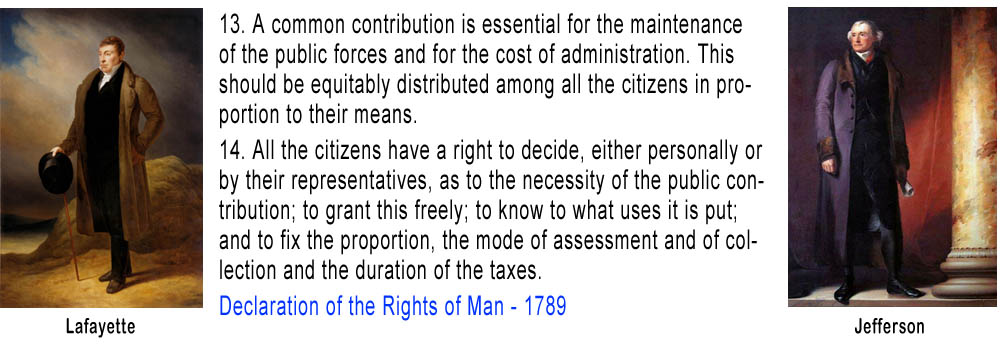
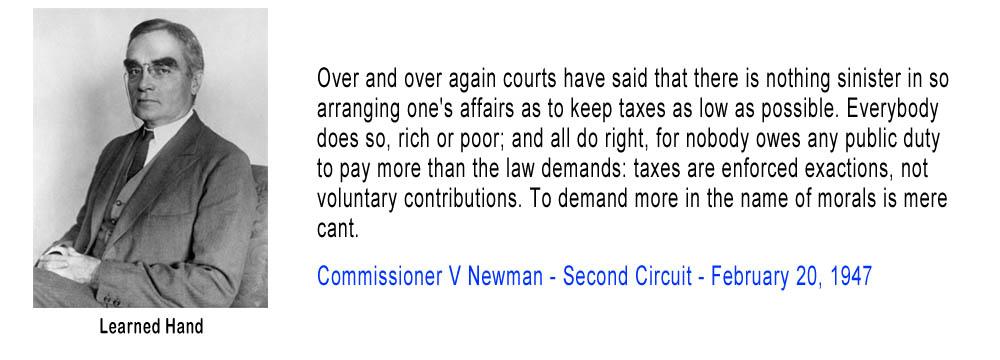
Over and over again courts have said that there is nothing sinister in so arranging one’s affairs as to keep taxes as low as possible. Everybody does so, rich or poor; and all do right, for nobody owes any public duty to pay more than the law demands: taxes are enforced exactions, not voluntary contributions. To demand more in the name of morals is mere cant.