IRS Chief Counsel Has To Decide If Nail Polish Is A Luxury
Taxpayer’s contributions of wrinkle creams, hair gels, perfumes, hair sprays, hair texturizers, curling irons, hair dyes, nail polishes, epilators, and hair restoration treatments (the “Donated Products”), are not “qualified contributions” that are eligible for the enhanced deduction under I.R.C. § 170(e)(3), because they are not needed for the care of the ill, the needy, or infants under I.R.C. § 170(e)(3)(A)(i) and Treas. Reg. § 1.170A-4A(b)(ii).
Bill Cassidy Providing Emergency Assistance To Wealthy Televangelists
On its face, providing a special tax benefit to “ministers of the gospel” seems blatantly unconstitutional, since it would only apply to Christians. The IRS early interpreted the statute more broadly to include many who would not otherwise want to be considered “ministers of the gospel” – rabbis and cantors for example. Hence the preservation of the clergy tax benefit has broad ecumenical support with, for example, Southern Baptists joining with the Russian Orthodox and Krishna Consciousness and Islamic organizations to file an amicus brief supporting the government’s appeal of Judge Crabb’s decision.
Follow Me
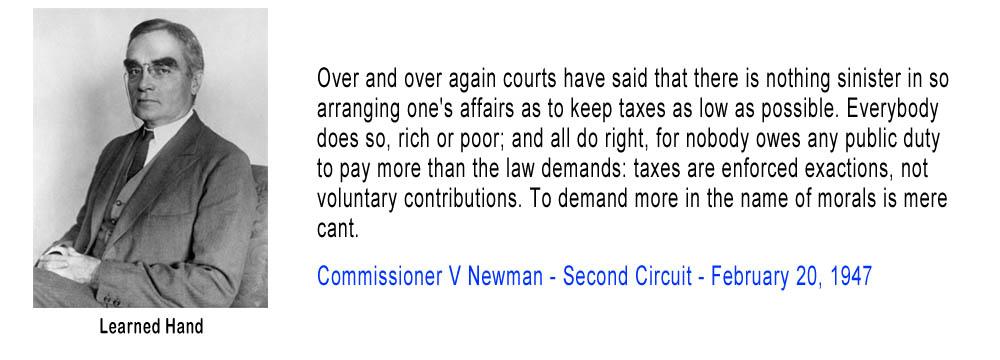
Over and over again courts have said that there is nothing sinister in so arranging one’s affairs as to keep taxes as low as possible. Everybody does so, rich or poor; and all do right, for nobody owes any public duty to pay more than the law demands: taxes are enforced exactions, not voluntary contributions. To demand more in the name of morals is mere cant.