






























































































Most Recent Posts
Detective’s Vacation And Sick Time Not Excluded From Taxable Income
Petitioners similarly cannot demonstrate that any of the 541 hours of unused vacation leave were accrued during his leaves of absence. Officers are limited to banking 200 hours of vacation leave per year and a total of 400. Mr. Speer had 541 hours of vacation leave at retirement because he had not yet lost vacation leave accrued during 2009. Just as with the sick leave, we would need to know Mr. Speer’s vacation history in order to determine whether any of the unused leave was accrued during his leaves of absence. Again, the record does not contain this information.
Kent Hovind Trials – Final Round Of The First Fight – Installment Four
Jonathan Schwartz continues his analysis of the final day of Kent Hovind's March trial along with some commentary on the Hovindication movement. No pictures for this...
New Player In The Kent Hovind Defense
Although Hovindicators tend to group me with the "enemy camp", I have a sincere wish that Kent Hovind would get out of prison sooner rather later. So I find the latest...
Superior Point Of Sale Software Does Not Mix Well With Skimming
Over the years, courts have developed a nonexclusive list of factors that demonstrate fraudulent intent. These badges of fraud include: (1) understatement of income, (2) inadequate maintenance of records, (3) implausible or inconsistent explanations of behavior, (4) concealment of assets or income, (5) failure to cooperate with tax authorities, (6) engaging in illegal activities, (7) an intent to mislead which may be inferred from a pattern of conduct, (8) lack of credibility of the taxpayer’s testimony, (9) failure to file tax returns, (10) filing false documents, (11) failure to make estimated tax payments, and (12) dealing in cash.
From The Boston Tax Institute
Lucien Gauthier has given me permission to reprint his e-mails to his customers. Here is the latest. In Larry Williams v. Comm., TCM 2015-76 (04/16/15), the Tax Court...
Heir Of Honduran Timber Fortune Wins Large Refund In Tax Court
The taxpayer win in this case is encouraging and you really have to wonder why the IRS pushed it so far. The actual intent of the passive activity loss rules was to kill traditional tax shelters. That is not what was going on there in any sense. The take-away from this case is that it would have been a really good idea for Mr. Lamas to have kept a contemporaneous log of his activities on behalf of Shoma. It is also worth noting that Jose Senior’s character building ownership structure of the businesses that he backed back-fired when it came to the passive activity loss rules, since it makes it impossible for someone to group all three as a single activity. You also have to wonder what Mr. Shoajee was thinking when he sent his follow-up letter to the IRS. Using the IRS as a weapon in a business dispute is, well, not good business.
Appomattox – April 2015 – Prequel
April 7 I started the day with that great road trip anticipation as I stumbled around the house making sure all my stuff was organized. I hit the road at...
Do Not Be Pressured Into Signing Last Minute Joint Return
Robin is a teacher, who receives a W-2 in January which is handed to Terry to be given to their accountant. Terry’s accountant really. Terry is a partner in a law firm and has a host of business interests making for a joint return that weighs several pounds. Once a year, Robin is summoned to sign – quickly, quickly, because we have to get it in the mail right away. Robin and Terry are splitting, but they were still married on December 31, 2014. Marital status for tax filing is determined as of the last day of the year.
Even in a pretty toxic marriage, each of the parties will have had some of their needs met. One of Robin’s needs that has been met in the marriage with Terry was worrying at all about tax compliance. As the marriage comes apart, there is a temptation to continue having some of those needs met even as you live apart. This can extend even to those needs as this article by Kristen Houghton title “Is Sex With Your Ex the New From of Monogamy?” indicates. Whatever the pros and cons of a post-marital roll in the hay might be, beginning with that last return of the marriage, Robin probably needs to take responsibility for tax compliance.
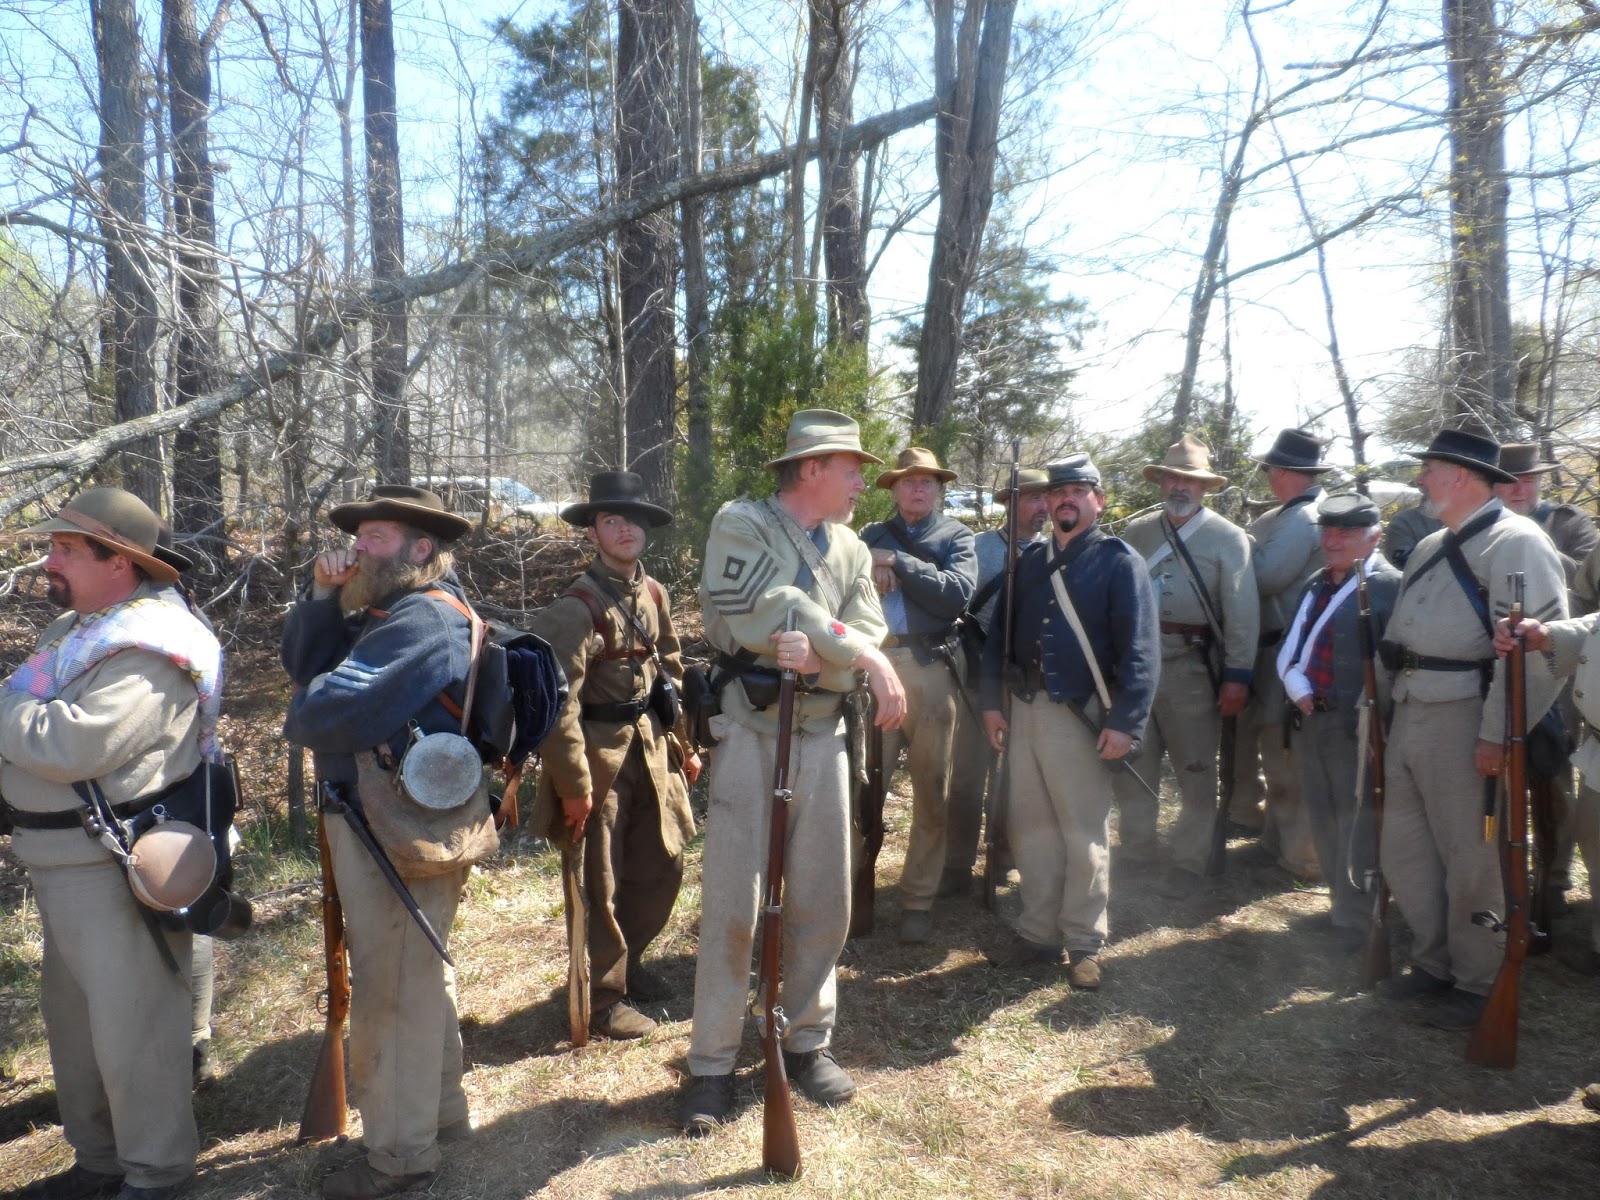
Appomattox – April 12, 2015 – Auld Lang Syne
Appomattox Court House National Historical Park - April 12, 2015 The final day of my Virginia trip, my last Civil War real time experience (The Grand Review Parade in...
Appomattox – April 11th – Freedom
The best anecdote about the Civil War I ever heard was one that I heard in Dublin. On our biggest vacation week ever, we went to the one Unitarian Church in Dublin, one...