






























































































Most Recent Posts
Wag The Dog
In the end, the capital gains tax had to be paid and apparently a 40% gross valuation overstatement penalty. Not to mention all the fees which were estimated to be around 20% of the “tax savings”. The really interesting question, though, is how much was lost due to stock being sold at less favorable prices than might have been obtained without the complications of the shelter planning?
Bring A Gun To School But You Better Have Insurance
This was originally published on October 20th, 2010 on PAOO. THOMAS MORE LAW CENTER v. OBAMA, God made the angels to show Him splendor, as He made animals...
Debit by the Window – Credit out the Window
Mr. Krause was a tax attorney and CPA who built his own Son of BOSS shelter. I have to wonder if he has two sides to his personality. Right now the CPA side is yelling “Language of 752, language of 752 – I knew it couldn’t work. The entry didn’t balance. You can’t get all that basis without crediting something.” The tax attorney side has answers. I can show you an example of a CPA making beautifully balanced entries that make no impression on judges, who are lawyers.
Welcome to the Sausage Factory – RTFI
Because Fidelity High Tech did not use cash cost to compute the stepped-up basis, it was required to attach an explanation to Schedule D. No such explanation was attached. An adequate explanation, as required by the instructions, would have included disclosure of the underlying transaction that resulted in the purported stepped-up tax basis used by Fidelity High Tech.
It’s Over
When this case was announced in the media earlier this year there was some vilification of Mr. Egan, which I really think was misplaced. Mr. Egan was part of the team of people that helped put men on the moon. His team of advisers believed that there were geniuses in the national firms that had figured out a legitimate capital gain strategy. In retrospect, it is easy to say that they should have realized the game was up when KPMG told them they had to disclose.
Sauce for the Goose
The court did not bother to remand the case back to appeals given the amount of time that had passed. The IRS behaviour in this case is rather disturbing. My bet would be that Dr. Byk did in fact file his second quarter 941 near the dawn of the millennium. Either way the IRS looks really lame, though, not being able to explain the codes on documents that they introduce as evidence. On the other hand it is heartening to know that the tax court is there for us in this situation.
They Also Serve
All the time that he wasn’t working at the power plant, he was “on-call” for his tenants. That should easily put him over the 750 hours. OK wise guys. He actually has to beat 1900 hours, because another condition is that you spend more time in real estate than anything else. Well by my reckoning the “on-call” theory could be another 6,000 hours.
Owe It to You or Cheat You out of It
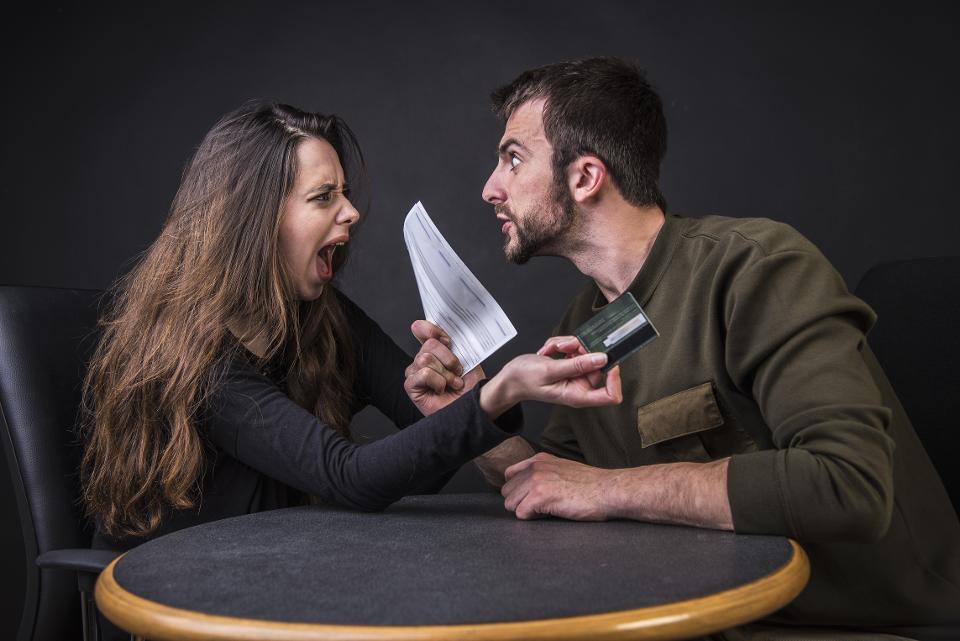
Filing a timely return even though you don’t have the money to pay the tax is definitely the right thing to do. When you are filing such a return, think before you make it a joint return. If you are the part of the couple who doesn’t have the income think three times.
The Mills of the Gods Grind Slowly
A partnership borrowed money from an operating company. The partnership then hired all the people who worked for the operating company and leased them to the operating company. The lease payments were deferred and the partnership was on the cash basis. When the partnership switched to the accrual basis it adopted a four-year spread.
Clock is Ticking On Amending Returns of Same Sex Couples
This will generally be more beneficial to the extent that there is a difference in the couple’s income. For example, if Robin and Terry each make $100,000, they will likely be better off single. If Robin makes $200,000 and Terry makes nothing a joint return will produce a lower tax. The way various exemptions, phase-outs, and limitations work, though, makes any general rule like that of limited applicability. If, for example, Robin had disallowed investment interest and Terry had investment income, a joint return might produce savings even if their incomes were equal. They only way to tell for sure is to run the numbers.