Anthony McCann1 360x1000
1theleasofus
1falsewitness
George M Cohan and Lerarned Hand 360x1000
lifeinmiddlemarch2
Adam Gopnik 360x1000
1lookingforthegoodwar
199
1empireofpain
Brendan Beehan 360x1000
2albion
1albion
lifeinmiddlemarch1
AlexRosenberg
Mark V Holmes 360x1000
10abion
14albion
4albion
Thomas Piketty3 360x1000
LillianFaderman
5albion
7albion
499
3albion
11albion
1lauber
7confidencegames
Learned Hand 360x1000
Thomas Piketty1 360x1000
3defense
Margaret Fuller 360x1000
8albion'
Storyparadox1
Betty Friedan 360x1000
Tad Friend 360x1000
Anthony McCann2 360x1000
Thomas Piketty2 360x1000
1trap
2lafayette
Richard Posner 360x1000
1gucci
3confidencegames
1paradide
1jesusandjohnwayne
Margaret Fuller4 360x1000
Margaret Fuller 2 360x1000
Maurice B Foley 360x1000
Margaret Fuller2 360x1000
1defense
5confidencegames
6confidencegames
2paradise
2lookingforthegoodwar
9albion
Office of Chief Counsel 360x1000
2falsewitness
Margaret Fuller1 360x1000
Mary Ann Evans 360x1000
2theleastofus
Margaret Fuller5 360x1000
Susie King Taylor2 360x1000
Spottswood William Robinson 360x1000
2defense
1madoff
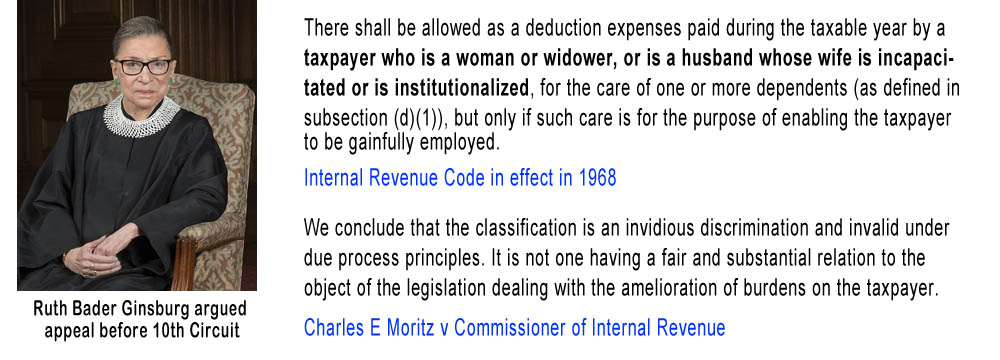
Ruth Bader Ginsburg 360x1000
3paradise
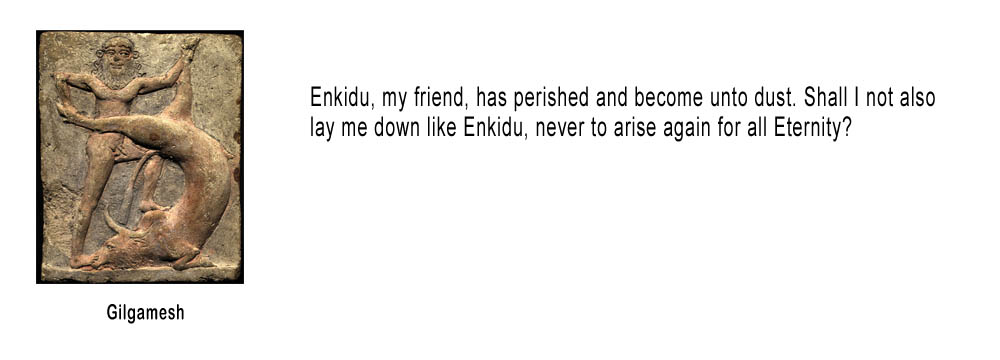
Gilgamesh 360x1000
11632
Edmund Burke 360x1000
Stormy Daniels 360x1000
1transcendentalist
James Gould Cozzens 360x1000
399
299
Susie King Taylor 360x1000
storyparadox2
2confidencegames
Margaret Fuller3 360x1000
6albion
2trap
2transadentilist
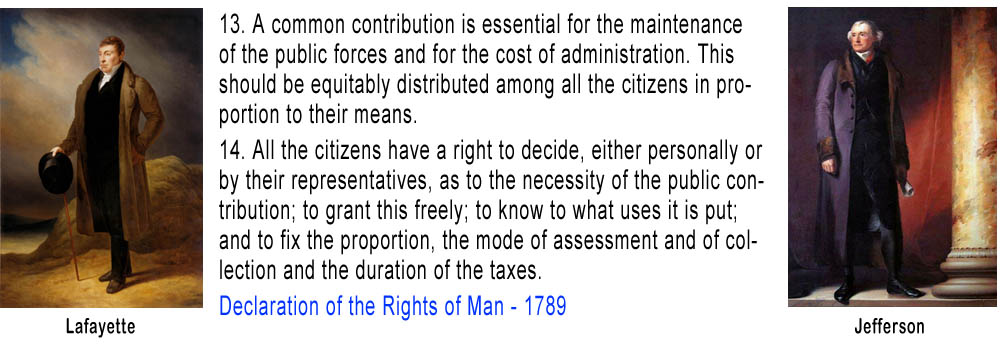
Lafayette and Jefferson 360x1000
2jesusandjohnwayne
George F Wil...360x1000
Maria Popova 360x1000
2gucci
13albion
3theleastofus
12albion
1lafayette
4confidencegames
storyparadox3
Samuel Johnson 360x1000
1confidencegames

Lucien Gauthier has given me permission to reprint his e-mails to his customers.  Here is the latest.

In Larry Williams v. Comm., TCM 2015-76 (04/16/15), the Tax Court applied Reg. 1.469-2(f)(6) to recharacterize the net rental income from rental real estate, which was rented by an S corporation which was wholly-owned by the taxpayer to a wholly-owned C corporation in which the taxpayer materially participated, as NONPASSIVE income.  If the taxpayer had owned the rental real estate individually or perhaps though a single member LLC, there would have been no question that -2(f)(6) applied, and the Tax Court concluded that owning the rental real estate through a wholly-owned S corporation should not change this result.  Sections 469 and 1411 may be the two hottest areas of tax practice today.  If you would like to learn more about section 469 from a Tax Attorney/CPA with two masters degrees in taxation and 28 years of experience with section 469, please attend our full day seminar on May 27 entitled Passive Activity Losses at the Hyatt house in Waltham!!!           
I’m behind on my reading thanks to tax season.  There is a good chance that I will find the Williams case to be forbes worthy.