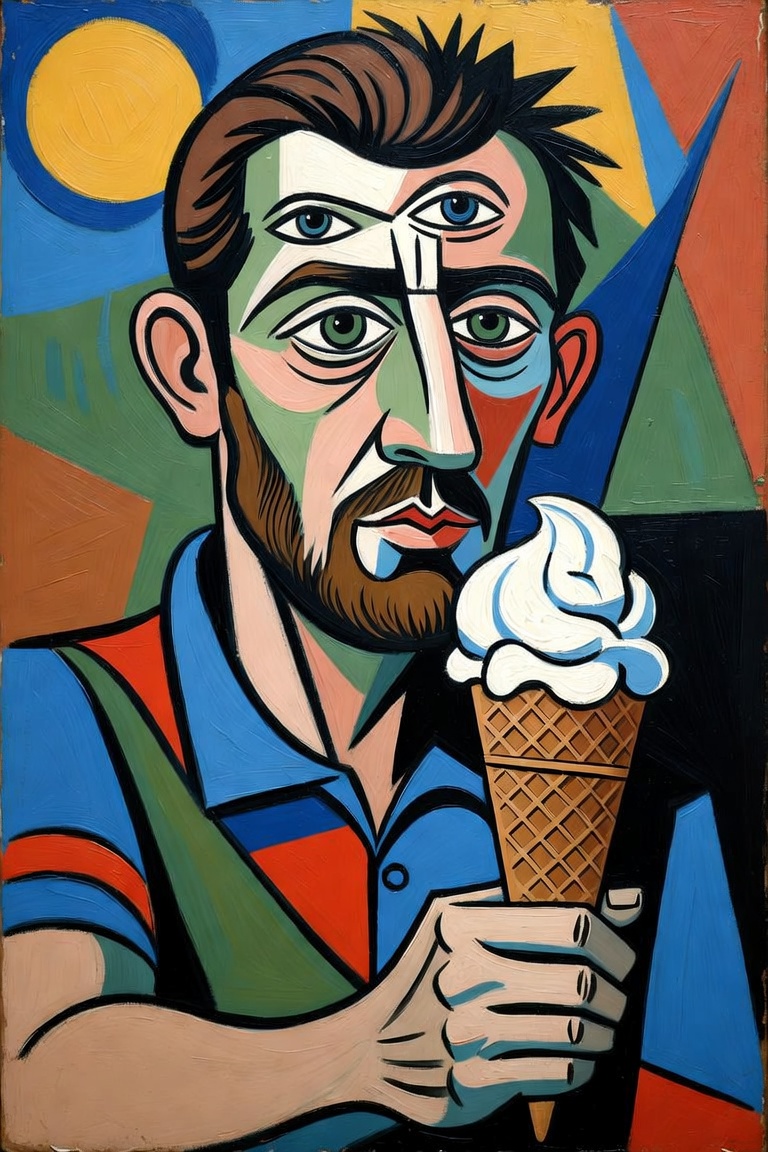
Image by Grok that looks nothing like the painting discussed in the opinion
I really like operating in a business environment where people trust one another and are trustworthy even though it sometimes can make doing the accounting a little challenging. That is why I find Judge Landy’s opinion in Tunkl v Comm. somewhat disturbing. The stakes were pretty high a $5,142,307 deficiency that turned on the treatment of a single transaction of $16.5 million. Was it a deposit? Was it a loan? Was it income? How do you characterize that kind of money that is wired to you with no paperwork?
The Handshake
I once attended an event where one of my clients was being honored by the business community he operated in. The guy had the highest standards of integrity that I had ever encountered. One of the people praising him said “He knows what a handshake means.” There actually is a significant amount of business efficiency that is picked up when you are doing business with people who you can trust and who trust you. That’s what I infer about the business relationship between David T. Tunkl and Robert Mnuchin that is outlined in the opinion. As we will see the informality can sometimes backfire.
Background
David Tunkl graduated from UCLA in 1977 and opened an art gallery in 1979, doing business as David Tunkl Fine Art (DTFA). Even after incorporating as Ganymede, a solely owned S corporation, he continued with DTFA as a DBA. Tunkl used a Ganymede JPMorgan Chase bank account for both business and personal expenses. I’m thinking of adding to my laws of tax planning, a prohibition on having personal and business transactions run through the same account.
Robert Mnuchin (1933-2025) graduated from Yale in 1955. After two years in the Army, he went to work for Goldman Sachs, becoming a general partner in 1967 and began heading the trading-and-arbitrage division in 1976. He joined the management committee in 1980. He retired in 1990 to pursue his interest in art. He opened a gallery in 1992 which with various name and partner changes remained operating until shortly after his death in 2025. Not really relevant to this story but of irresistible interest is the fact that Mnuchin’s second son Steven Mnuchin, also a Yalie (Class of 1985) and Goldman Sachs veteran was Secretary of the Treasury during Trump 1.0 (2017-2021). Perhaps the way to make a small fortune in the art business is to start with a large fortune.
Tunkl became acquainted with Mnuchin and began a business relationship that consisted of him buying paintings for the gallery that were then resold at a substantial profit. There were 13 transactions totaling more than $100 million. There were usually no written agreements between them. Presumably there was a handshake at least metaphorically.
Picasso And An Ice Cream Cone
According to the opinion, Mr. Tunkl discussed purchasing the Pablo Picasso painting Man with Ice Cream Cone with Mnuchin. There could be a bit of a mystery here as “Man with a straw hat and an ice cream cone” has been owned by the Picasso National Museum – Paris since 1979. They were probably talking about another version that is floating around. Or maybe, somebody was planning a heist, which would really make the story interesting. Let’s go with the other version concept.
Although there were Picassos in Mnuchin’s collectiton, the ice cream cone painting was not for him. The idea was to acquire the work for $18.5 million and flip it to a Swiss buyer for either $30.5 million or $18.5 million plus a Jean Dubuffet Paris Circus painting worth $13 million. Mnuchin was to put up $16.5 million and Tunkl $2 million. After getting their capital back, they would split profits 75/25 in favor of Mnuchin going to 50/50 over $30 million. There was no formal agreement in place when Mnuchin wired $16.5 million to Ganymede on January 11, 2018. A backdated invoice was created in May 2018.
While working on the Picasso deal, Tunkl was also trying to buy a Francis Bacon painting, Figure Turning. He was also looking to sell another contemporary painting for $250,000,000 which would have earned him a commission between $15 and $18 million. That did not work out. So Tunkl ended up using the $16.5 million to complete the Bacon purchase rather than forfeit a $4.4 million deposit. In April, Tunkl learned that the Picasso owner was no longer interested in selling.
Tunkl realized he could not pay back the $16.5 million. He flew to New York to explain that things had gone very badly. He ended up signing an agreement that indicated that there were six paintings including the Picasso that he had failed to sell or buy for Mnuchin and that he personally and Ganymede owed Mnuchin $44 million. Early in 2019 Tunkl transferred an interest in a U.K. company worth $2.5 million in partial satisfaction of the $44 million, but never paid anything else on the debt.
Ganymede passed a loss of $1,696,516 to Tunkl on its 2018 return. According to the opinion the $16.5 million was not reported in “any manner”. I’m not sure if that means that it was not included in liabilities. Anyway treating that amount as revenue was apparently the only audit adjustment.
The Ruling
Put simply, the burden of proof was on Tunkl to establish that the $16.5 million was not income. And in Judge Landy’s view Tunkl did virtually nothing to make his case:
“Next, Mr. Tunkl’s obligation to repay Mr. Mnuchin did not arise at the time the $16.5 million was wired. While Mr. Tunkl testified that he had an obligation to repay Mr. Mnuchin from the start, in support of this contention Mr. Tunkl offered merely his testimony, which was unreliable, unsupported, and thoroughly unconvincing. To the contrary, the documentary evidence provided to the Court (i.e., the backdated invoice, Agreement, and Note) demonstrates that Mr. Tunkl’s obligation to repay the $16.5 million did not arise until months later when the deal fell through,”
On the question of whether the payment was a loan rather than a customer deposit, Judge Landy stated the factors that are considered in the Ninth Circuit, where an appeal would go.
“1) whether the promise to repay is evidenced by a note or other instrument; (2) whether interest was charged; (3) whether a fixed schedule for repayments was established; (4) whether collateral was given to secure payment; (5) whether repayments were made; (6) whether the borrower had a reasonable prospect of repaying the loan and whether the lender had sufficient funds to advance the loan; and (7) whether the parties conducted themselves as if the transaction were a loan.”
Apparently in Judge Landy’s view, Tunkl went 0 for 7.
“The $16.5 million the Gallery paid to Ganymede is not a loan for federal tax purposes because the terms of the unsettled transaction bear no indicia of a loan.”
Judge Landy concluded:
“Mr. Tunkl used the $16.5 million at will and derived economic benefit from it because he was unable to purchase the Bacon painting without those funds. As a result, the $16.5 million is taxable income to Mr. Tunkl, as Ganymede’s sole shareholder, unless an exclusion applies.”
Why I Think IRS Might Have It Right
It is not clear whether the $2.5 million was against the $16.5 million or something else. So Tunkl apparently either paid nothing on the $16.5 million or, at most, a bit over 15%. Mnuchin had the right to sue him but never did. So even if it were a deposit or loan, there should come a point where he recognizes the income, if he doesn’t pay it back. Picking up the income when he received the money, given that Ganymede was a cash basis taxpayer is clearer than any other point you might pick. On the other hand picking up the income when he used the money for something other than buying the Picasso has some merit and the same bottom line.
Why I Think The IRS And The Judge Might Have It Wrong
Reading the whole story, it is altogether improbable that when Mnuchin wired the $16.5 million, he did not think that he had a deal with Tunkl. And apparently this sort of informality is not unusual in the high-end art business. Art market journalist, Tim Schneider wrote about it in 2017, while discussing another transaction that had gone bad.
“I’m pretty confident that, if even the most grizzled veterans in the art industry believed they were in line for $10 million based on the sale of a piece of real estate, a mega-yacht, or an ownership stake in a company, it would take a massive head injury to prevent them from lawyering up and getting the deal on paper. Make the asset in question a piece of art, though, and suddenly even “the Mick Jagger of art auctions” (sorry, couldn’t resist) sees no problem in gambling that same colossal payday on a dice-roll called “mutual trust” between alleged gentlemen.
Look, de Pury has been playing this game a lot longer and at a much higher level than I have. His attorney was also absolutely correct when he wrote that, in the art market, it’s not at all “unusual to find some types of contract made orally.” Even at enormously high dollar values, people in this industry have been doing things in a “gentlemanly manner” rather than a formally agreed one for generations.”
There is even a sentiment that this is the way the art business is supposed to be as you can see in this article by Francesca Kaye Augustine in Medium.
“If you’re looking at the art market through a traditional business lens, you’re already missing the point. This isn’t an industry that scales like tech startups or responds to conventional marketing strategies. It’s an ecosystem of cultural workers, solo artists, and passionate collectors who have quietly built one of the world’s most valuable and enduring markets — not despite its small-scale nature, but because of it.”
This is all consistent with the argument in Tunkl’s brief.
“The obligation to repay was initially based on Tunkl’s and Mnuchin’s prior manner of conducting business. Mnuchin had previously advanced funds to Tunkl with little to no documentation. (FOF 34-35) When the Picasso transaction went bad, Tunkl’s preexisting obligation to repay became an express debt and was formalized in the demand note in June of 2018 which Tunkl signed. (FOF 89-91) This debt was then reiterated when the notes were restructured in December 2018, and reiterated again in the July 2022 affidavit. (FOF 98-100, 107-109) Tunkl further transferred a business interest to Mnuchin in partial repayment of the debt. (FOF 102-106) There can be no income where there was always an obligation to repay and funds were considered by both parties to be a debt.”
Lew Taishoff covered the opinion and advanced a theory of how he might have litigated it.
“Now for my second-guess. There’s a $5 million deficiency, plus chops and add-ons, on the table. Why not scare up a few experts from the art world to testify as to the custom and usage of the trade, business, or occupation? If such be the case, let them testify that everything is done on a handshake, that trust among dealers is the essence of the business, that no piece of paper is a shield to a breach of trust, that routinely millions of dollars transfer between on-and-offshore banks on nothing more than a phonecall between dealers. Might save the deposit argument. Or even joint venture.”
The Moral Of The Story
This story illustrates two of my laws of tax planning. The 16th law is: Being right without substantiation can be as bad as being wrong. And backdated substantiation is not really substantiation. The other has more ambiguity to it. it is the Prime Directive : If you don’t have documentation, at least have a plausible story. The ambiguity is that to me with forty years in not so big time accounting the idea that Tunkl and Mnuchin had a real deal is altogether plausible. Adam B. Landy has been on the Tax Court for five years. His prior experience since graduating from law school was working in a large law firm and being a senior attorney with IRS Office of Chief Counsel. What is plausible to him is a little bit different maybe.
Other Coverage
As noted Lew Taishoff covered the case with The Art of The Art.
Jason Freeman does a nice summary at Freeman Law. He focused on a footnote that I admit I overlooked. The Judge noted that the arrangement had elements of a joint venture but nobody brought that up.
Ed Zollars had a piece in Current Federal Tax Developments. He notes:
The decision by Judge Landy offers an instructive analysis of the economic dominion doctrine, the strict temporal requirements for establishing customer deposits under Commissioner v. Indianapolis Power & Light Co., and the Ninth Circuit’s multifactor framework for bona fide debt under Welch v. Commissioner.
David Brunk has a really good piece on Tax Court Blog.
“The Tax Court’s opinion in Tunkl is notable not only for its substantive holding but also for its assertion of judicial power over the IRS. The court took pains to emphasize that it was not bound by the formalities of the parties’ agreement but instead looked to the substance of the transaction. This approach aligns with the court’s longstanding role as the final arbiter of tax disputes, a role the Supreme Court has repeatedly affirmed.”
One small point. Brunk has the opinion being by Albert Lauber, but looking at the docket and the opinion I think it is clearly Adam Landy.
For great value in continuing professional education check out the Boston Tax Institute.
If you would like to do business with Your Tax Matters Partner email yourtaxmatterspartner@gmail.com