Lafayette and Jefferson 360x1000
Margaret Fuller5 360x1000
1madoff
1falsewitness
6albion
1jesusandjohnwayne
1lauber
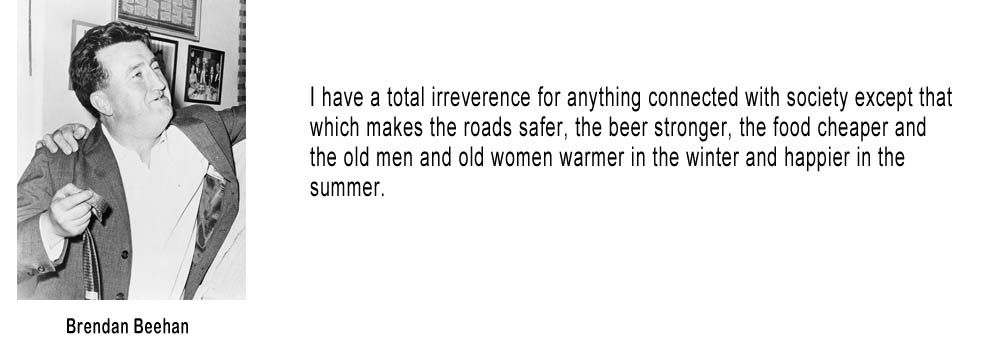
Brendan Beehan 360x1000
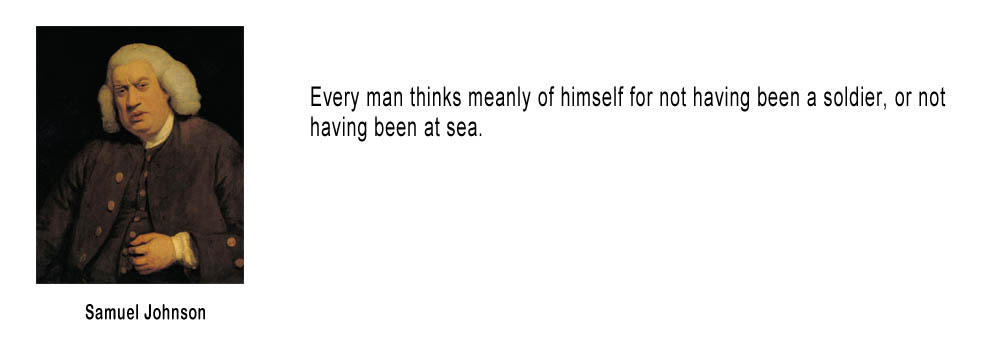
Samuel Johnson 360x1000
LillianFaderman
1lookingforthegoodwar
Betty Friedan 360x1000
James Gould Cozzens 360x1000
storyparadox3
Margaret Fuller4 360x1000
Thomas Piketty3 360x1000
1gucci
9albion
1transcendentalist
299
8albion'
13albion
Learned Hand 360x1000
2confidencegames
2jesusandjohnwayne
2theleastofus
2falsewitness
1empireofpain
2trap
1albion
Thomas Piketty1 360x1000
Edmund Burke 360x1000
2lafayette
3theleastofus
George F Wil...360x1000
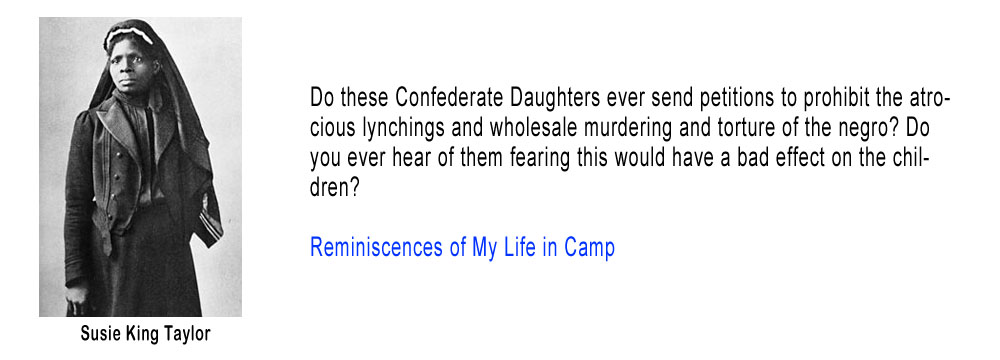
Susie King Taylor 360x1000
2gucci
1defense
Maria Popova 360x1000
5confidencegames
Spottswood William Robinson 360x1000
Gilgamesh 360x1000
399
4albion
1trap
11albion
Storyparadox1
3albion
Margaret Fuller 2 360x1000
Margaret Fuller1 360x1000
Office of Chief Counsel 360x1000
Anthony McCann1 360x1000
11632
Susie King Taylor2 360x1000
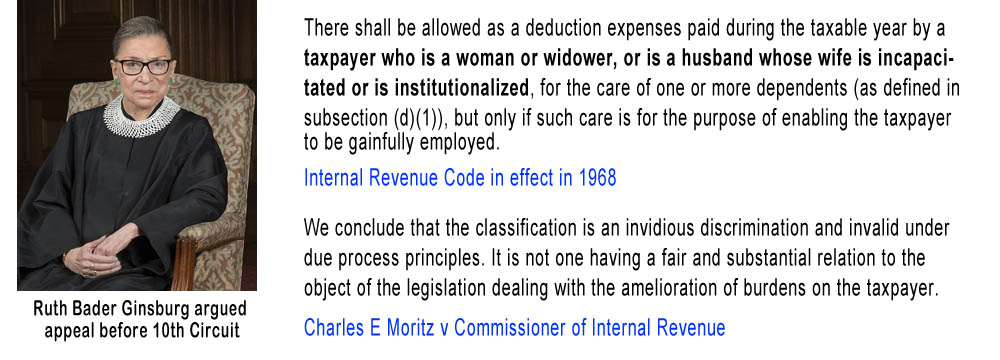
Ruth Bader Ginsburg 360x1000
storyparadox2
AlexRosenberg
5albion
12albion
2albion
4confidencegames
7confidencegames
499
Margaret Fuller2 360x1000
199
10abion
14albion
Maurice B Foley 360x1000
Stormy Daniels 360x1000
Tad Friend 360x1000
3defense
1confidencegames
2paradise
2transadentilist
Margaret Fuller 360x1000
Mark V Holmes 360x1000
3confidencegames
2defense
Mary Ann Evans 360x1000
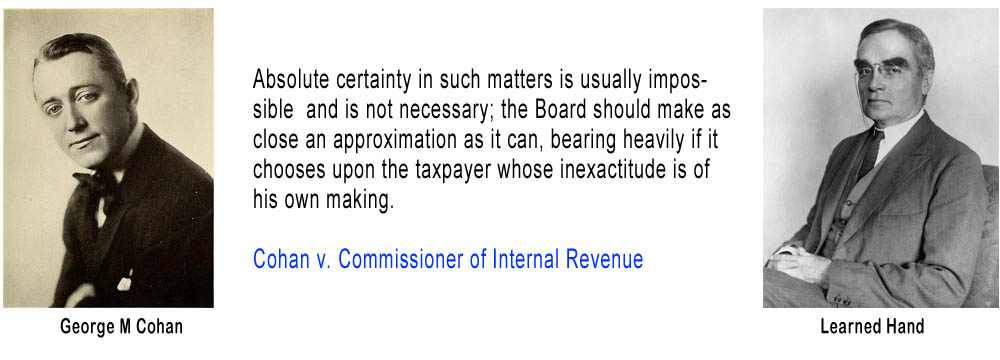
George M Cohan and Lerarned Hand 360x1000
1paradide
3paradise
1theleasofus
Thomas Piketty2 360x1000
Adam Gopnik 360x1000
Anthony McCann2 360x1000
1lafayette
Margaret Fuller3 360x1000
Richard Posner 360x1000
7albion
2lookingforthegoodwar
lifeinmiddlemarch2
6confidencegames
lifeinmiddlemarch1

$99.00

This is a 2-hour live video conference (2 CPE credits) led by Peter J. Reilly, CPA., who has been a tax practitioner for over 44 years, has read and analyzed over 700 cases on hobby losses.

Zoom Live Video Conference: Nov. 14th, 1-3pm ET
 
Because one of our objectives is to replicate the live in-person interactive seminar experience, you can unlock your microphone, and questions and comments are expected and encouraged before, during, and after the presentation until everybody taps out!

Section 183 “Activities not engaged for-profit” often referred to as the hobby loss rule has been part of the Internal Revenue Code for over 50 years. Over that half-century, it has produced some fascinating case law that continues to be relevant. We will discuss the nine factors that are used to assess the taxpayer’s intent and how the courts have evolved in the view of what satisfies the factors. We will discuss how to be alert to hobby loss exposure, how to be prepared for an audit, and how to fight an audit when it happens. From horse breeding to Amway to playing the slots using the principles of Feng Shui, we will look at who wins, who loses and why, and how you can help your clients be winners with their losses. After a forty-year career in public accounting focused on tax, Peter now writes for Forbes.com and has covered hobby loss cases extensively.

USE THIS LINK TO REGISTER

For a roundup of my hobby loss coverage check out Hobby Loss Roundup.


For great value continuing professional education.  I recommend the Boston Tax Institute
You can register on-line or reach them by phone (561) 268-2269 or email vc@bostontaxinstitute.com.  Mention Your Tax Matters Partner if you contact them.